
Patrick's Quick Answer
Moving from Austin to San Antonio is a same-state move, so the biggest tax rule does not change: Texas has no state income tax in either city, and the property tax playbook is identical. What changes is mostly price and pace. The Austin city median home price sits near $550,000 while San Antonio's sits near $265,000 (Redfin, three months to August 2026), and because tax rates and prices are separate inputs, the same monthly payment supports a very similar home price in both cities. The real differences show up in the commute, the dollar size of your tax bill, the employment landscape, and what your cash to close looks like, not in a new set of rules.
I work this corridor from both sides: I originate home loans statewide across Texas and sell real estate around Greater San Antonio, so I see the Austin-to-San Antonio move from the financing and the contract side at once. Here is the honest comparison, with the numbers dated and the sources named.
Why this particular move keeps happening
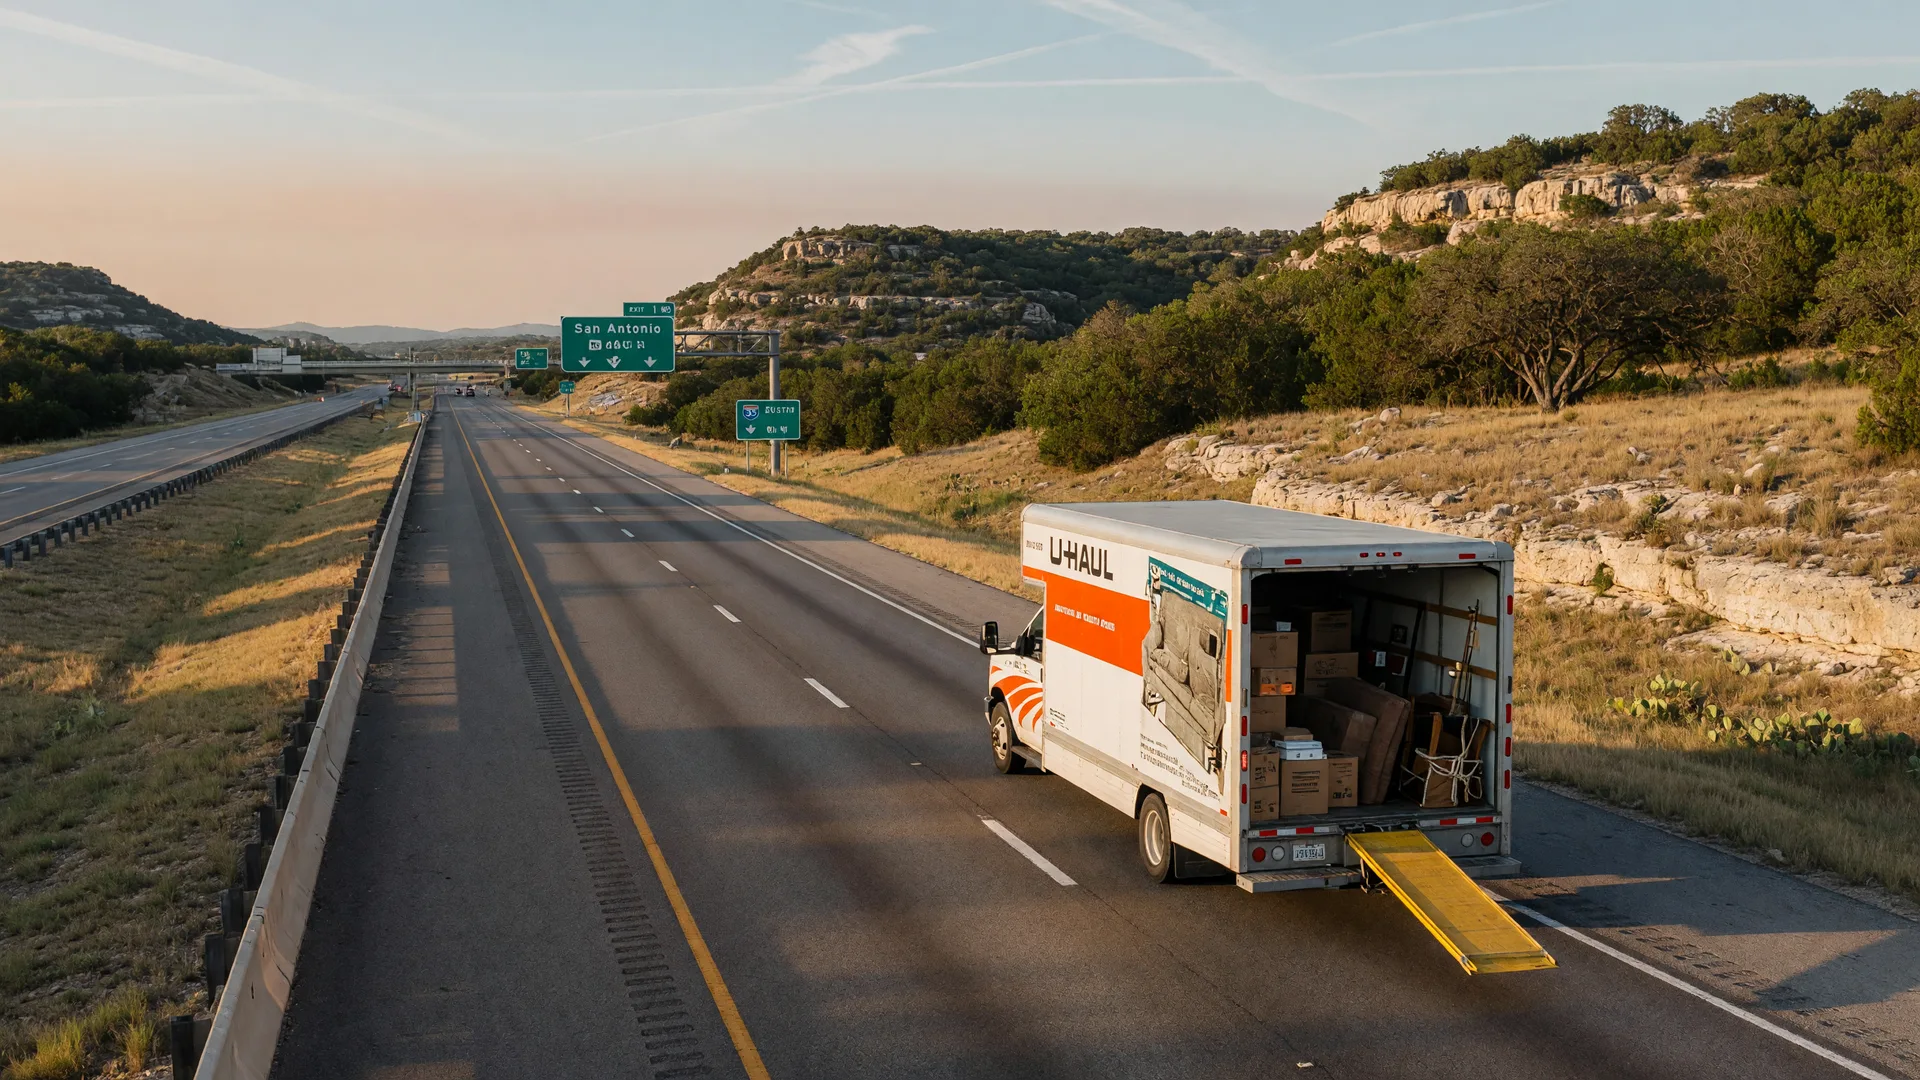
The Austin-to-San Antonio move is one of the most common relocation questions I get, and it is not a mystery. San Antonio is about 75 miles south on I-35, close enough for weekend visits to old friends, yet priced at a level where a buyer's dollar goes measurably further. Redfin has tracked homebuyers priced out of Austin turning to San Antonio, and the city's own employment mix gives the move staying power: San Antonio's anchors include the military and federal footprint around JBSA, the healthcare cluster around the South Texas Medical Center, and financial services including USAA, while Austin leans heavily on state government, the University of Texas, and technology.
For most families this is not a lifestyle leap. It is a deliberate trade: a smaller monthly outlay, a bigger or newer house, and a different pace, in exchange for a longer drive back to the places you already know. Neither city is better; they answer different questions, and the rest of this post is about answering yours with numbers instead of impressions.
The two markets, side by side
Start with the dated price picture, then layer the other costs on top. These are single-tracker snapshots from Redfin for the three months ending August 2026, so treat them as a directional market read, not a forecast and not a per-home number:
| Metric and period | Austin | San Antonio |
|---|---|---|
| Median home sale price, city (Redfin, three months to Aug 2026) | about $550,000 | about $265,000 |
| Year-over-year change | down about 1% | down about 1.9% |
| Broader-area note | Austin MSA full-year 2025 median closed near $438,532 (KUT / Statesman) | Bexar County median closed near $281,500 (Aug 2026) |
| 20% down payment on the city median | about $110,000 | about $53,000 |
| Cost of living index, US average 100 (BestPlaces, 2026) | about 129 | about 91 |
Two honest caveats. First, a city-wide median hides a wide range of neighborhoods in both places, so the median is orientation, not a shopping list. Second, different trackers measure differently: if you see a lower Austin figure, it is usually the MSA or a county-wide number rather than the city figure quoted here. The gap between the two cities is large under every method; the exact size depends on which definition you use.
Cost of living: where the gap actually comes from
Cost of living indexes do not agree on one number, which is normal. Redfin puts Austin only about 5% costlier overall, Numbeo (March 2026) puts San Antonio roughly 6% to 12% cheaper depending on whether rent is included, and BestPlaces (2026) puts the gap near 40% because housing carries more weight in its index. What every source agrees on is the driver: housing. Groceries and restaurants are close to a wash, and utilities run modestly higher in Austin, around 17% higher per Redfin, which makes sense given the bigger average home and different utility providers.
Because this is a same-state move, one of the usual cost-of-living levers does not move at all: Texas has no individual state income tax in either city. That will already be reflected in your Austin paycheck, so shifting to San Antonio does not create a tax windfall. The advantage here is in the housing numbers and the smaller dollar tax bill, not in a new income-tax structure.
Property taxes: the same playbook, different dollar bills
Both cities run on the same Texas system: the county appraisal district sets the appraised value, and the city, county, school district, and any special districts each add a rate. The property tax system explained applies equally to a Travis County home and a Bexar County home. What differs is the rate mix and the price underneath it.
- Typical combined in-city rate, per $100 of value, before exemptions (tax year 2025): around 2.05% for a typical Austin home in Austin ISD, around 2.27% for a typical San Antonio home in SAISD. San Antonio's higher example is driven mainly by the school district levy plus community college and health districts.
- Average effective rates (SmartAsset county medians): about 1.34% in Travis County versus about 1.54% in Bexar County. Effective rates divide the actual bill by market value, so they are the fairer apples-to-apples comparison.
Here is the part that surprises people: San Antonio carries the higher typical rate of the two, yet because the median home costs less than half as much, the median San Antonio tax bill in dollars is far lower than the median Austin bill. Rate and price are separate inputs, and this move changes the price far more than it changes the rate. Also note that the seller's current tax bill never predicts yours: exemptions are applied to the buyer's name and timing, and the homestead exemption filing is a step to plan, not assume.
One more layer applies in both cities: MUD and PID assessments. Austin-area master-planned communities commonly add roughly $0.25 to $1.50 per $100 of assessed value on top of the base bill, and some Travis County communities carry total rates near 2.6% to 2.7%. San Antonio has its own MUD communities, including Alamo Ranch and Johnson Ranch on the north side. The rule is identical on both ends: read the appraisal district record for the exact address and count any MUD or PID assessment in the complete payment.
The same budget in both cities: the payment math
Let's run the comparison the way a buyer actually thinks about it: with one monthly budget, pointed at each city. The math below is illustrative, rounded, and dated September 2026. It assumes a 30-year fixed loan at an illustrative 6.5% rate with 20% down, and it uses the effective property tax rates above. This is example arithmetic for comparison, not a rate quote, not a tax quote, and not an approval number for your file. Insurance and HOA dues are excluded because they are property-specific and must be quoted.
| Same budget, both cities | Austin | San Antonio |
|---|---|---|
| Home price that a $2,400/month budget supports (P&I plus property taxes) | about $344,000 | about $335,000 |
| 20% down payment on that price | about $68,800 | about $67,000 |
| How that price compares with the city median | below Austin's about $550,000 median | above San Antonio's about $265,000 median |
The counterintuitive result: holding the rate, down payment, and tax-load assumptions steady, the same monthly budget supports a very similar home price in both cities, because San Antonio's higher typical tax rate eats up most of the price advantage when you force the payment to be equal. The real difference is what you get for that price relative to each city's median. The same monthly payment buys a home comfortably above the San Antonio median, and it buys a home well below the Austin median.
| The payment at each city's median price | Austin at $550,000 | San Antonio at $265,000 |
|---|---|---|
| Principal and interest, illustrative 6.5%, 20% down | about $2,780 | about $1,340 |
| Property taxes at approximate effective rates | about $615 | about $340 |
| Homeowners insurance and HOA | not quoted, property-specific | not quoted, property-specific |
| Rough combined monthly total, before insurance and HOA | about $3,400 | about $1,680 |
Buy the median house in each city with the same assumptions and the monthly difference is real: roughly $1,700 a month before insurance and HOA, driven almost entirely by the price gap. Statewide rate averages hide street-level variation, so the complete monthly payment, including the escrow for taxes and insurance, is the number that matters, and it is always property-specific. That is where the pre-approval conversation starts: on your real inputs, not example math.
Cash to close: where your dollars actually go
The down payment is the headline, but cash to close is the sum of everything you bring on closing day: down payment, loan fees, title and escrow charges, prepaids for the first year's insurance and tax escrow, and any prorations. The Texas closing costs for buyers and the cash to close breakdown both apply to any Texas purchase; what differs between these two cities is the size of the loan and the prepaids underneath it.
Here is the concrete version: at 20% down on the city median, the down payment alone is about $110,000 in Austin versus about $53,000 in San Antonio, and the property tax and insurance prepaids scale down with the lower price too. For a first-time buyer the same move can work with FHA at 3.5% down, VA at 0% down where eligible, or USDA at 0% down on eligible addresses, and Texas down payment assistance can cover part of the gap. The honest planning step is the same regardless of city: get the complete cash-to-close number for the specific home, not just the price tag, before you write an offer.
The commute reality on I-35
The distance is about 80 miles by road, roughly 1 hour 15 minutes to 1 hour 30 minutes in free-flow traffic, and over 2 hours in weekday rush hour, with the slowest stretches around the Austin metro, San Marcos, and New Braunfels. Austin is regularly ranked among the most congested US cities for traffic, and the I-35 stretch through Austin repeatedly lands on the list of Texas' most congested roadways, so the commute time is a function of when you go, not just where you live. Most buyers who make this move do not drive it daily; they keep a hybrid schedule, remote work, or ties that only need a weekend drive.
The corridor itself matters too. I-35 takes you straight through San Marcos and New Braunfels, so the in-between stops are real towns, not empty highway. If you do plan a regular commute, test your actual route at the time you would drive it, several times, before choosing a neighborhood. My San Antonio commuter guide covers the corridor choices and what to expect directionally.
Climate and everyday life: a smaller change than you think
Both cities sit in the same humid subtropical climate zone, and the differences are minor. Summer highs average around 95 to 97 degrees in Austin and about 95 in San Antonio; January lows run about 38 to 42 degrees in Austin and 39 to 41 in San Antonio. Rainfall is similar, with Austin slightly wetter at about 35 inches a year versus about 33 inches in San Antonio. Triple-digit days used to be more common in Austin, but recent averages have converged, with both cities now seeing roughly 27 to 30 days above 100 degrees a year. The heat is real on both ends, the air conditioning is a fact of life in both, and the move will not change your wardrobe.
Where you land in San Antonio
Austin buyers land all over the San Antonio area, and the honest answer is that the right corridor depends on your commute, your budget, and your preferred property type. Four corridors cover most of the range, and each has a full guide on this site:
- US-281 north, Bulverde and Spring Branch: larger lots and Hill Country terrain, with much of the corridor unincorporated, so wells, septic, and utility districts are common. Bulverde guide.
- I-10 west, Boerne and Fair Oaks Ranch: a town with its own services plus master-planned communities that cross Kendall, Bexar, and Comal County lines. Boerne guide.
- I-35 northeast, New Braunfels, Schertz, and Cibolo: town and suburban homes with city services, the closest big-city corridor to the highway back to Austin. New Braunfels guide.
- Canyon Lake: lake-country acreage and resort-style communities in unincorporated Comal County. Canyon Lake guide.
Each corridor carries its own county, school district, appraisal district, utility mix, and tax jurisdictions, so the comparison is never "town versus town" but "exact address versus exact address." The relocation hub compares all the corridors on the complete monthly payment without making a universal winner claim, because there is not one.
Questions buyers ask before this move
Can I use my Austin home equity to buy in San Antonio? Tap to expand
Does financing change because I am moving within Texas? Tap to expand
Can I live in San Antonio and keep working in Austin? Tap to expand
Is now a good time for an Austin buyer to move to San Antonio? Tap to expand
Making the move? Let's put the numbers on paper.
I work the financing and the real estate side of the same move, so the price, the tax load, the cash to close, and the offer strategy get coordinated in one plan. Bring your Austin numbers, and I will show you what they do in San Antonio.
A buyer who moved this route put it this way: "He's very responsive, professional, and will clearly explain every step of your buying process, and best of all he was able to keep some money in my pocket." More client words are on the reviews page.
About Patrick Kevin Fagan, REALTOR®
Patrick Kevin Fagan is a Texas Real Estate Sales Agent (#454749) with AXEN Realty LLC and a Senior Loan Officer (NMLS ID #877741) with NEXA Lending. He brings 23+ years in mortgage lending and 19 years in real estate, serving homebuyers, homeowners, and sellers across Greater San Antonio and the Texas Hill Country, and originates home loans statewide across Texas.
Sincerely, Patrick Kevin Fagan
Answered by Patrick Kevin Fagan
Texas Real Estate Sales Agent #454749, AXEN Realty LLC · Senior Loan Officer, NMLS ID #877741, NEXA Mortgage, LLC
Call or text: 210-317-6514
Updated September 25, 2026. Median price, cost of living, and tax figures are dated, single-tracker snapshots (sources listed in the post) and are directional, not forecasts or quotes. Payment math is illustrative arithmetic for comparison using a stated assumption set, never a rate quote or an approval. Verify the appraisal district record, tax rates, utility types, HOA documents, and school district for the exact address before you commit. Nothing here is neighborhood steering or a claim that any area is better for any person or group; area fit is personal, and fair housing law applies to every inquiry.
