

You found the house, your offer got accepted, and now the title company wants thousands of dollars above your down payment. Closing costs in Texas are where first-time buyers lose their composure, because nobody warns them the check has three parts. Let's fix that, Patriot Nation, before you sign anything.
Quick Answer
Closing costs in Texas live in three buckets: the down payment, transaction costs (roughly $5,500 to $6,000 on a $300,000 purchase), and prepaids plus escrow (roughly $4,000 to $4,500). Only the appraisal and the inspection are paid before closing, and they are the only at-risk money.
Get help lowering your cash to close in Texas.
The three buckets of closing, in plain English
Every dollar you bring to the closing table goes into one of three buckets. The term is simple, the meaning matters, and the dollar impact is where buyers get blindsided:
- The down payment. This is your ownership stake, the chunk of the purchase price you pay from your own cash instead of borrowing it. Bucket one is the one everyone budgets for.
- Transaction costs. These are the closing costs proper: lender charges, title insurance and escrow fees, the appraisal, the credit report, recording fees. This bucket buys the loan and the clean transfer of the title.
- Prepaids plus escrow. Property taxes, homeowners insurance, and prepaid interest collected at closing. This bucket is money going into your own future bills, not fees, which is exactly why it surprises people.
The real-world consequence: if you only saved for the down payment, you are missing two-thirds of the picture. Buckets two and three are where the "closing costs" line on your Loan Estimate comes from.
What Texas transaction costs really run on a $300,000 purchase
Run the math on a $300,000 purchase and the transaction-cost bucket typically lands at roughly $5,500 to $6,000. That number covers lender fees (origination, underwriting, processing), the title policy and escrow fee, and third-party charges like the appraisal and the credit report.
Here is the beat: the lender lines are the ones you can actually shop. Two Loan Estimates for the same house can differ on lender fees by a thousand dollars or more, while the title and third-party lines stay close to the same. Compare the estimates line by line and that difference stays in your pocket.
Prepaids and escrow: roughly $4,000 to $4,500 you are pre-paying
On that same $300,000 purchase, the prepaids and escrow bucket typically runs roughly $4,000 to $4,500: a slice of property taxes, the first year's homeowners insurance premium, and prepaid interest from your closing date to the first payment.
These lines show up on the Closing Disclosure no matter which lender you pick, because they are not fees at all. They are money going to the county, your insurance company, and the interest clock on your own loan. The dollar impact is real, but the money is working for you, not disappearing.
What is paid before closing: the only at-risk money
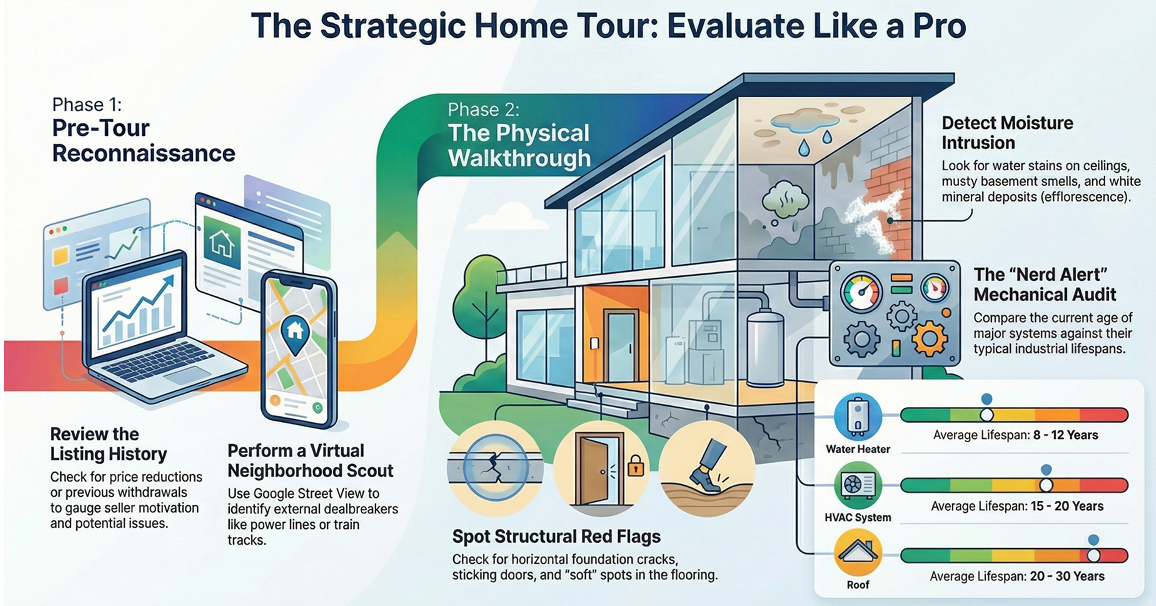
Two costs come out of your pocket well before the closing table: the appraisal and the home inspection. The lender orders the appraisal, typically around a few hundred dollars, and you hire the inspector yourself, typically a few hundred more.
Those two are the only at-risk costs in the deal. If the transaction falls apart for a covered reason, your earnest money comes back and the rest of your cash to close never gets collected, but the appraisal and the inspection are spent either way. Budget for them as spent money and the surprise evaporates.
The worked example: your real out-of-pocket total
Stack the buckets side by side on that $300,000 purchase: a 3.5% down payment near $10,500, transaction costs around $5,500 to $6,000, prepaids and escrow around $4,000 to $4,500. Round numbers, the out-of-pocket total lands near $20,000, and then your earnest money deposit comes back as a credit, so the cash you actually wire nets lower.
Then the shrink happens. Seller concessions can cover a big share of the transaction costs, down payment assistance can cover the down payment and more, and the two together can take a $20,000 out-of-pocket number down to a fraction of itself. That is the whole game in Texas, planned in advance.
Patrick's closing-cost beat
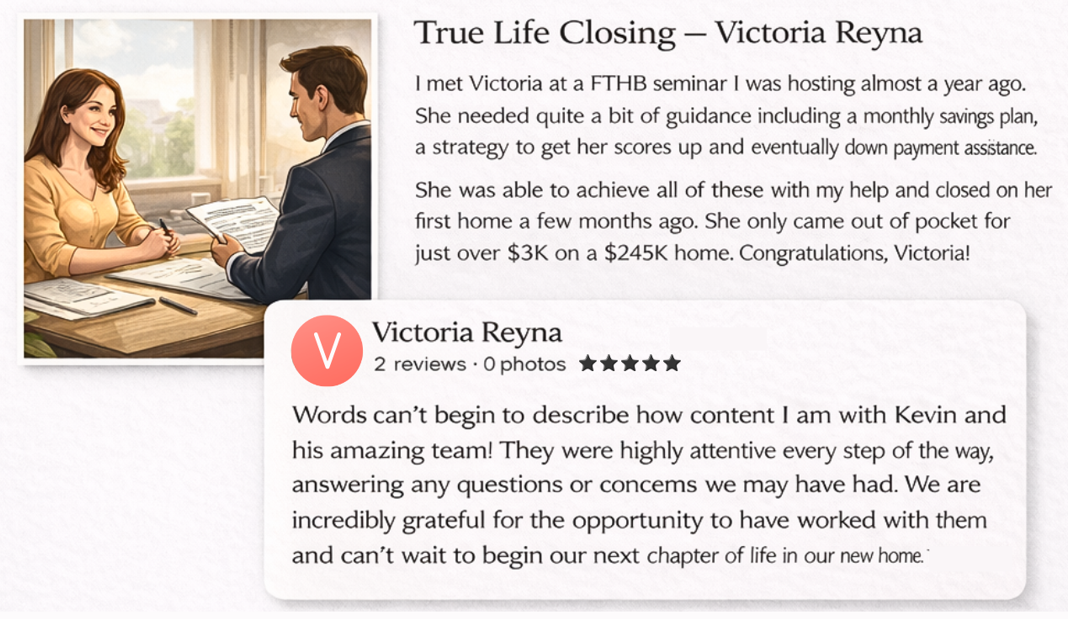
Here is my honest track record, straight from the desks I work: on purchases at or under $300,000 with an FHA loan, seller concessions plus down payment assistance, I get buyers to the closing table under $7,000 in cash, not the $20,000 the buckets first suggested.
That is not a promise on your specific deal, because every contract and every program has its own rules. It is a target the structure makes realistic, and it starts with knowing all three buckets before you write an offer. That is what being on your side looks like.
Watch Patrick break down a low-cash-to-close FHA purchase
This is the strategy conversation I have at the kitchen table: FHA financing, seller concessions, down payment assistance, and what the cash to close actually bottoms out at. Grab a pen and let's run the numbers on camera.
Read the full transcript of this video, word for word. Or watch it on Patrick's YouTube channel.
Ask Patrick about Texas closing costs
Get a clear breakdown of closing costs buyers pay in Texas and what you can negotiate.
