
Your pre-approval says you can afford the payment, so why is the lender now asking for a pile of cash at the table? Because the payment and the cash to close are two different numbers in Texas, and the second one is the one buyers forget to plan. Let's put a real number on it right now.
Quick Answer
Cash to close is the total cash you bring to the table: the down payment, transaction costs, and prepaids plus escrow, minus seller concessions, lender credits, your earnest money, and down payment assistance. It is the number on the Closing Disclosure, delivered at least three business days before closing.
Get help lowering your cash to close in Texas.
What cash to close means, exactly
Cash to close is not your down payment alone. It is the all three buckets minus the money already in the deal. Start with the down payment, add the transaction costs (lender, title, and third-party fees), add prepaids plus escrow (taxes, insurance, prepaid interest), then subtract seller concessions, lender credits, your earnest money deposit, and down payment assistance. Whatever is left is the wire you actually send.
The real-world consequence: two buyers can buy the same priced house with the same loan and bring very different cash, because concessions, credits, and deposits move the number. That is why the estimate exists, and it is why you plan the whole equation, not just the down payment.
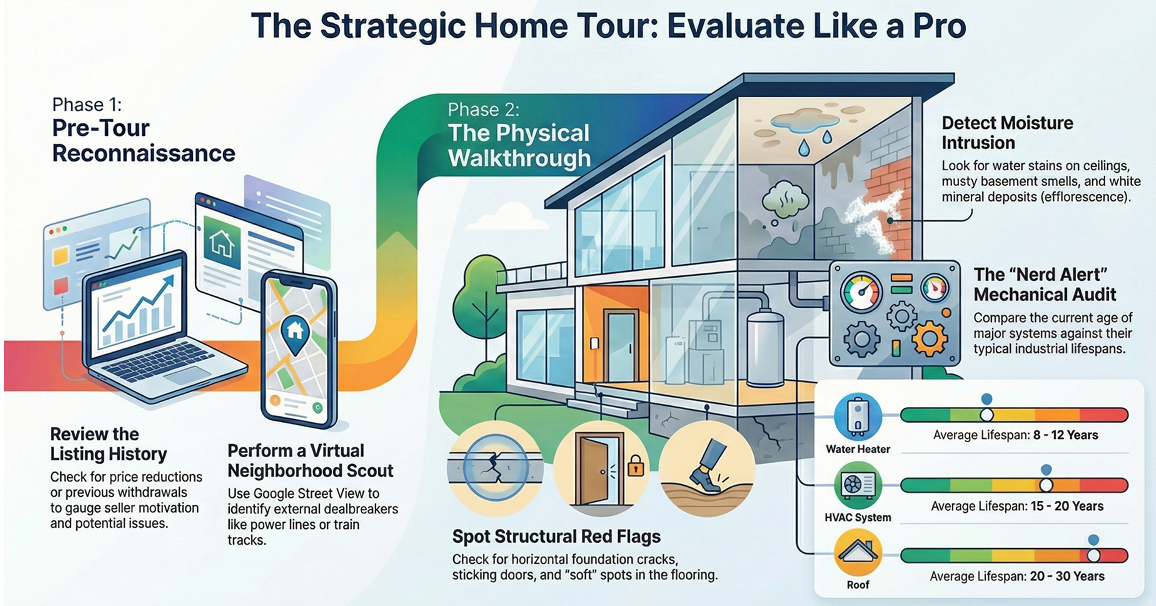
The realistic Texas number on a $300,000 purchase
Take a $300,000 purchase and run the full gap: a 3.5% FHA down payment near $10,500, transaction costs around $5,500 to $6,000, prepaids plus escrow around $4,000 to $4,500. Before any credits the cash to close looks like roughly $20,000, which scares buyers off every week.
Then subtract what actually gets subtracted: seller concessions cover a large share of the transaction costs, down payment assistance can cover the down payment, and your earnest money comes back as a credit. FHA plus concessions plus DPA routinely pushes that number under $7,000. That is the realistic Texas number for a well-structured deal at or under $300,000.
A real Closing Disclosure example: $262,000, zero down
Here is a real file out of my desk, the kind of math I run weekly on a VA purchase: a $262,000 home, zero down. The seller chips in $4,600 in concessions, and your $2,600 earnest money deposit comes back as a credit. The Closing Disclosure ends up asking for roughly $240 out of pocket at the table.
That is the power of structuring the deal instead of just shopping the payment. Zero down, seller money doing the heavy lifting, your earnest money working twice, and the cash you bring collapses to a couple hundred dollars.
The 3-business-day Closing Disclosure rule
Your lender must deliver the Closing Disclosure at least three business days before closing. That document is the final math, the number the title company will actually collect, and it is the number you budget against, not the earlier estimate.
Here is the beat: if something changes on the disclosure in ways the rules define as significant, the three-day clock restarts. That is a protection on your side. Read it the day it arrives, compare it to the Loan Estimate, and ask about every line that moved before signing. The number on the disclosure is the number, so make it your number before the appointment.
How to bring cash to close down
Three levers move the needle, and a good loan officer pulls all three at once:
- Seller concessions. Negotiate the seller to contribute toward your closing costs in the contract, up to the limit your loan program allows. This is the biggest single lever.
- Down payment assistance. Texas programs can cover the down payment, closing costs, or both, and most of them plug into FHA loans.
- Shopped lender fees. Origination, underwriting, and processing lines vary lender to lender. Two Loan Estimates can differ by a thousand dollars or more on lender fees alone.
Pull all three and the $20,000 number starts looking like a $7,000 number, or less on the right structure. Pull none and you bring six figures of stress to the table.
The wire-fraud warning before you send a cent
Wire fraud is real, and it hits right here. Hackers intercept the email chain, pose as the title company, and send you "updated" wiring instructions with their own account number. Buyers who follow the email alone have wired their entire cash to close into a criminal's account.
The rule is simple and non-negotiable: never wire money on an email alone. Always call a verified phone number, the one you already have from the title company or your loan officer, confirm the account details by voice, and hang up before any money moves. If instructions change, the conversation changes first.
Watch Patrick break down a low-cash-to-close FHA purchase
This is the same strategy conversation I have across the desk: FHA financing, concessions, down payment assistance, and what the final wire really is. Grab a pen and follow the math on camera.
Read the full transcript of this video, word for word. Or watch it on Patrick's YouTube channel.
Ask Patrick about cash to close in Texas
Get a clear breakdown of exactly what you will bring to closing and how to plan for it.
