
Patrick's Quick Answer
With rates over 7%, San Antonio builders are advertising rates as low as 3.375% to 4.99%. Those numbers are not the same deal. Some are permanent, some last one or two years, and some are adjustable. A permanent fixed rate usually wins if you plan to stay. Closing-cost cash can win if you're short on funds. Either way, the builder's rep works for the builder. Don't sign until you have your own agent reviewing the numbers and the contract. Talk to Patrick before you sign.
Don't Sign With a Builder Until We Talk.
The friendly sales rep in the model home works for the builder, not for you. Their job is to protect the builder's price, push the builder's lender, and sell you upgrades at the builder's markup.
My job is to protect you. As your buyer's agent, I will:
- Get you every incentive available, plus the ones that aren't advertised
- Compare the builder's rate offer against outside financing, so you know which one actually saves you money
- Negotiate the price, the lot premium, the design credits and the closing costs
- Review the builder's contract with you before you sign, because it's written to protect them
- Stay with you through construction, inspections and the final walkthrough
You don't pay me anything out of pocket. In most cases the builder pays my commission at closing. You get your own representation at no cost to you.
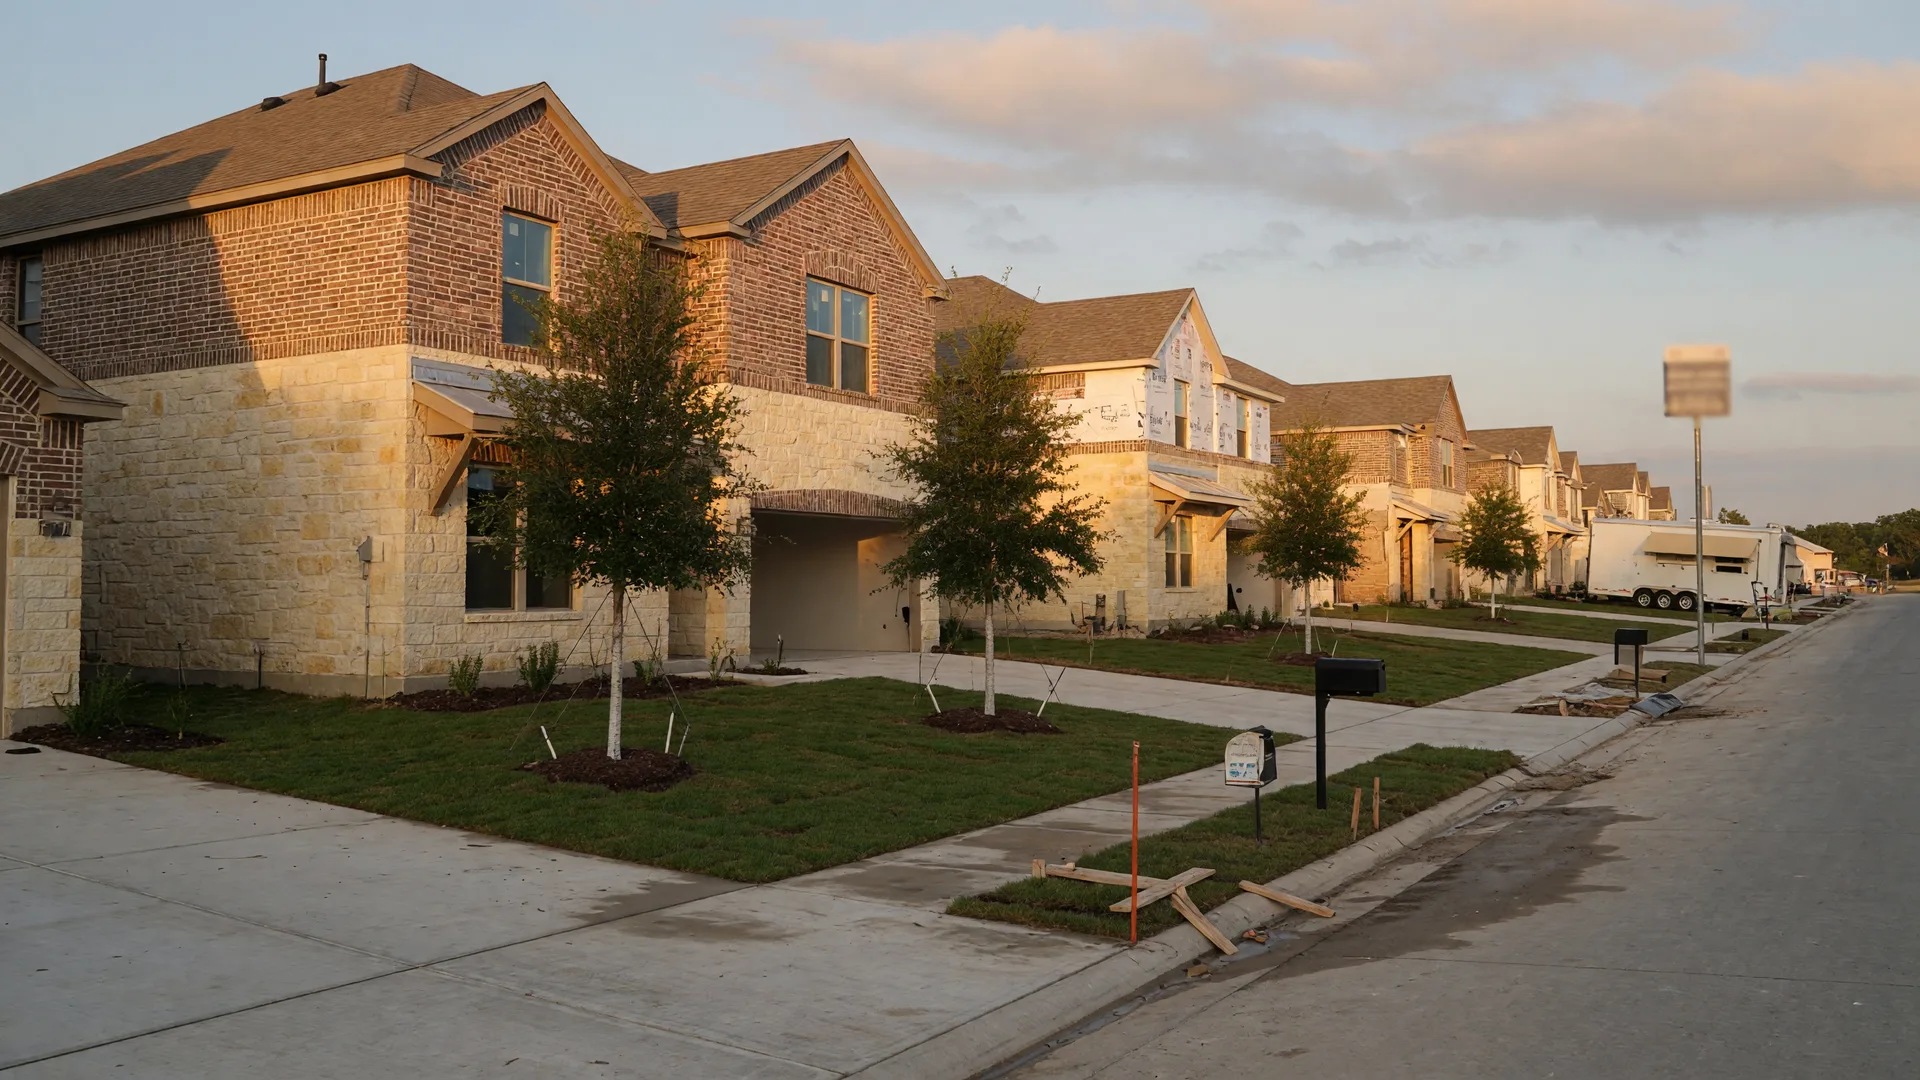
Patriot Nation, if you have looked at a new home in San Antonio this fall, you have seen the billboards: 3.49% this year, 4.99% fixed, $10,000 in closing costs. Those numbers are real, but they are not comparable, and buyers who take the first pretty number without reading the structure are the ones who get surprised at year three. This article decodes each type of builder incentive, shows you what it actually costs, and explains why you should talk to a buyer's agent before you ever sign a guest card.
Why Builders Are Offering Big Incentives While Rates Are Over 7%
Mortgage rates just hit a one-year high. Freddie Mac's Primary Mortgage Market Survey put the 30-year fixed average at 7.03% for the week of September 24, 2026, up from 6.95% the week before and 6.30% a year earlier. See the Freddie Mac PMMS data here.
Higher rates slow sales, and builders would rather buy the rate down than cut the price. A price cut on one home drags down appraisals across the whole community, which hurts every lot they can still sell. An incentive, by contrast, is a financing tool aimed at one buyer and one contract, so builders push them hard instead.
Timing matters too. Builders push hardest in the fourth quarter: D.R. Horton's fiscal year ends September 30, and Perry runs a Year End Sales Event. That is a good time to buy, and also a high-pressure time at the sales desk. The pressure is exactly why you want your own representation before you walk in.
Watch Patrick's newest video, 2 Reasons First-Time Home Buyers Are Choosing New Builds Right Now, for why first-time buyers are choosing new builds and how to negotiate them.
The 4 Types of Builder Incentives (and What Each Really Costs)
Every offer falls into one of four buckets. Each one changes your payment, your cash to close, or both. Each row below carries its verified date, because every one of these offers changes weekly.
1. Permanent Rate Buydown
The builder pays points to lower the rate for the entire loan. Example: Perry Homes advertises a 4.99% 30-year fixed rate (5.178% APR) bought down with points through Crestmark or Parkstone Mortgage.
The catch: the incentive budget goes to points, so you usually give up flex cash, and the headline rate is only available with the builder's financing. Confirm the APR and the points on the Loan Estimate, because the APR is the number that reflects the true cost.
Best for: buyers who plan to stay long term and want a payment that never steps up.
Perry Homes offer verified Sept 29, 2026 on perryhomes.com (Summer Sales Event 2026, San Antonio page). Financing through Crestmark Mortgage Company or Parkstone Mortgage.
2. Temporary 2-1 Buydown
The rate is lowered for the first two years, then steps up. Example: Coventry Homes has advertised a 2-1 buydown at 3.49% year 1, 4.49% year 2, 5.49% after (APR 6.281%) through Jet HomeLoans.
The catch: the payment rises for two straight years. Coventry's own example shows about $466 more per month by year 3, and that step-up hits right when your other costs are settling in.
Best for: buyers who expect income to grow in the first few years.
Coventry 2-1 buydown example advertised late September 2026; the current San Antonio Sales Event (verified Sept 29, 2026 on coventryhomes.com/san-antonio/sales-event-listing/) now advertises low rates from 3.99%. Confirm the current structure in writing before you rely on a teaser rate.
3. Adjustable-Rate Teaser
A low rate locked for a set number of years, then adjustable. Example: Lennar has run promotional FHA 5/1 ARMs at 3.375% (APR about 6.8%) through Lennar Mortgage.
The catch: the rate is fixed for 5 years, then it adjusts. The APR tells the real story on an ARM, because it spreads the adjustment risk over the loan term. On the illustrative comparison below you will see a 5/1 ARM at 3.375% reset to a payment near $2,700 at year six.
Best for: buyers who know they will sell or refinance within 5 years.
Lennar San Antonio offers verified Sept 29, 2026. The current Fall Super Sale promo runs through Lennar Mortgage; 2026 San Antonio promos have advertised FHA fixed rates from 3.75% (4.587% APR) to 4.25% (5.391% APR) plus price reductions up to $25,000. Confirm the current rate sheet on the live promo page.
4. Closing-Cost Credits and Flex Cash
Cash applied to your closing costs, or flexible cash from the builder. Current examples: D.R. Horton up to $8,000 in closing costs through DHI Mortgage, Meritage up to $10,000 through MTH Mortgage, and Perry up to $35,000 in flex cash on its Summer Sales Event.
The catch: you pay the full market rate. The credit is real money, but it is a one-time amount, while a buydown saves you money every month for years.
Best for: buyers who are short on cash to close.
Offers verified Sept 29, 2026: D.R. Horton San Antonio pages (special pricing and up to $8,000 in closing costs with DHI Mortgage through December 31, 2026), meritagehomes.com/state/tx/san-antonio (Get Moving Sales Event), perryhomes.com (Summer Sales Event 2026). All require the builder's affiliated lender.
Side by Side: One $450,000 Home, Four Different Deals
This is the comparison that matters. Same home, same loan amount, four different incentive structures. The table is labeled the way every honest comparison should be:
Assumptions: $450,000 price, 5% down, $427,500 loan, 30-year term, principal and interest only (no taxes, insurance, mortgage insurance, or HOA). Market rate 7.03% (Freddie Mac PMMS, week of September 24, 2026). ARM assumed to reset to 7.00% in year 6 for illustration.
| Offer | Year 1 | Year 3 | Year 6 | 5-year P&I total |
|---|---|---|---|---|
| Permanent 4.99% fixed | $2,292 | $2,292 | $2,292 | $137,538 |
| 2-1 buydown (3.49/4.49/5.49%) | $1,917 | $2,425 | $2,425 | $136,256 |
| 5/1 ARM at 3.375% | $1,890 | $1,890 | about $2,704 (if 7%) | $113,398 (then resets) |
| Market 7.03% + $10K closing costs | $2,853 | $2,853 | $2,853 | $171,167 ($161,167 after the $10K credit) |
A permanent 4.99% saves about $560/month versus the market rate, for the life of the loan.
The 2-1 looks cheapest in year 1, but the payment climbs about $500/month by year 3.
The ARM looks cheapest for 5 years, then could jump about $800/month.
$10,000 in closing costs is real money, but at the full market rate it costs far more over 5 years than a buydown.
The right answer depends on the buyer's cash, credit and how long they'll stay. That's exactly what Patrick runs for them.
The builder's lender isn't always the best deal. Send me the offer and I'll show you the real numbers.
Text Me the OfferInteractive Tool
Builder Offer Decoder
Plug in your numbers and up to three builder offers. The tool compares monthly P&I, the 5-year cost, and what each incentive is really worth versus today's market rate. Clean, plain math, no clutter.
Prefilled with the Freddie Mac 30-year average, week of Sept 24, 2026. Editable.
Loan amount: $427,500
Offer 1
Offer 2
Offer 3
Want me to run this with your real numbers and the builder's actual Loan Estimate?
Don't Sign With a Builder Until We Talk.
The friendly sales rep in the model home works for the builder, not for you. Their job is to protect the builder's price, push the builder's lender, and sell you upgrades at the builder's markup.
My job is to protect you. As your buyer's agent, I will:
- Get you every incentive available, plus the ones that aren't advertised
- Compare the builder's rate offer against outside financing, so you know which one actually saves you money
- Negotiate the price, the lot premium, the design credits and the closing costs
- Review the builder's contract with you before you sign, because it's written to protect them
- Stay with you through construction, inspections and the final walkthrough
You don't pay me anything out of pocket. In most cases the builder pays my commission at closing. You get your own representation at no cost to you.
The Preferred-Lender Catch
Nearly every incentive requires the builder's affiliated lender, and often their title company. You cannot be forced to use their lender to buy the home, but you usually lose the incentive if you don't.
Here is the honest part: sometimes the builder's lender is the best deal. Sometimes the "special rate" comes with higher fees or points that eat the savings. The only way to know is to compare Loan Estimates line by line: rate, APR, points, lender fees, and total cash to close. The builder's lender can quote a great rate and still lose on points; your lender can quote a higher rate and win on credits. The label on the door never decides the winner, the numbers do.
I'm a loan officer too. I'll put the builder's Loan Estimate next to an outside quote and tell you honestly which one wins. If the builder's lender wins, I'll tell you to take it.
Want the full comparison framework? See how Patrick compares the builder lender vs an outside lender on the New Construction hub, or read the builder's lender vs your own lender article.
Builder Incentives by Area (Fall 2026)
Incentives vary by corridor because the builders and the inventory differ. Every row below was verified from the builder's own site on Sept 29, 2026, and every offer can change before the end of the week. Rates shown always carry their APR and key assumptions.
Far West and Northwest San Antonio
The most builder-dense corridor in the metro: Stillwater Ranch, Nopal Valley, Davis Ranch, Ladera, Summerlin, Thomas Pond, Sagebrooke, Kallison Ranch, Briggs Ranch, and Hunters Ranch. Most builders, most move-in-ready homes. See the full Far West corridor guide.
| Builder | Current advertised offer | Verified |
|---|---|---|
| Perry | Summer Sales Event 2026: up to $35,000 seller-paid flex cash plus a $5,400 special incentive; financing through Crestmark or Parkstone Mortgage. | Sept 29, 2026 |
| Meritage | Get Moving Sales Event: up to $10,000 in closing costs on select homes; MTH Mortgage and Carefree Title required. | Sept 29, 2026 |
| Lennar | Fall Super Sale through Lennar Mortgage; 2026 San Antonio promos have advertised FHA fixed rates from 3.75% (4.587% APR) to 4.25% (5.391% APR) plus price reductions up to $25,000. | Sept 29, 2026 |
| D.R. Horton | Special pricing and up to $8,000 in closing costs on select San Antonio area homes through December 31, 2026, with DHI Mortgage. | Sept 29, 2026 |
| Coventry | San Antonio Sales Event: low rates advertised from 3.99% (5.899% APR example) and savings up to $143,000 on select move-in-ready homes. | Sept 29, 2026 |
| Chesmar, David Weekley, Highland | No current public incentive verified in this build. Send Patrick the builder quote and he will compare it against the financing and the full deal. | Sept 29, 2026 |
Schertz and Cibolo
The I-35 northeast corridor that serves JBSA-Randolph and many VA buyers: Homestead, The Parklands, Foxbrook, Legendary Trails, Rhine Valley, The Crossvine, and Saddlebrook Ranch. See the full Schertz and Cibolo corridor guide.
| Builder | Current advertised offer | Verified |
|---|---|---|
| Coventry | San Antonio Sales Event: low rates advertised from 3.99% (5.899% APR example) and savings up to $143,000 on select move-in-ready homes. | Sept 29, 2026 |
| Meritage | Get Moving Sales Event: up to $10,000 in closing costs on select homes; MTH Mortgage and Carefree Title required. | Sept 29, 2026 |
| Lennar | Fall Super Sale through Lennar Mortgage; 2026 San Antonio promos have advertised FHA fixed rates from 3.75% (4.587% APR) to 4.25% (5.391% APR) plus price reductions up to $25,000. | Sept 29, 2026 |
| Perry | Summer Sales Event 2026: up to $35,000 seller-paid flex cash plus a $5,400 special incentive; financing through Crestmark or Parkstone Mortgage. | Sept 29, 2026 |
| Highland, Chesmar, Beazer, Starlight | No current public incentive verified in this build. Send Patrick the builder quote and he will compare it against the financing and the full deal. | Sept 29, 2026 |
New Braunfels, Seguin and Marion
The widest price range in the metro: Mayfair, Veramendi, Meyer Ranch, Sunflower Ridge, Kyndwood, Steelwood Trails, Navarro Ranch, and Grace Valley. See the full New Braunfels and Seguin corridor guide.
| Builder | Current advertised offer | Verified |
|---|---|---|
| Lennar | Fall Super Sale through Lennar Mortgage; 2026 San Antonio promos have advertised FHA fixed rates from 3.75% (4.587% APR) to 4.25% (5.391% APR) plus price reductions up to $25,000. | Sept 29, 2026 |
| Perry | Summer Sales Event 2026: up to $35,000 seller-paid flex cash plus a $5,400 special incentive; financing through Crestmark or Parkstone Mortgage. | Sept 29, 2026 |
| Coventry | San Antonio Sales Event: low rates advertised from 3.99% (5.899% APR example) and savings up to $143,000 on select move-in-ready homes. | Sept 29, 2026 |
| Highland, DRB, Scott Felder, David Weekley, Pulte, Del Webb | No current public incentive verified in this build. Send Patrick the builder quote and he will compare it against the financing and the full deal. | Sept 29, 2026 |
Bulverde, Spring Branch and Boerne
Up US-281 and I-10 West the market is mostly custom and semi-custom, so rate promotions are fewer and the incentives are quieter. The exceptions worth naming: Perry at Johnson Ranch and Kinder Ranch in the Spring Branch and Bulverde area, and Meritage at Fox Falls in Boerne. If a builder here is showing a rate promotion, it is usually tied to one phase or a handful of inventory homes. See the Bulverde and Spring Branch guide and the Boerne and Fair Oaks Ranch guide.
| Builder | Current advertised offer | Verified |
|---|---|---|
| Coventry | San Antonio Sales Event: low rates advertised from 3.99% (5.899% APR example) on select homes. | Sept 29, 2026 |
| Meritage | Get Moving Sales Event: up to $10,000 in closing costs on select homes. | Sept 29, 2026 |
| Perry | Summer Sales Event 2026: up to $35,000 seller-paid flex cash plus a $5,400 special incentive. | Sept 29, 2026 |
| Lennar | Fall Super Sale through Lennar Mortgage; see the current San Antonio promo page for this week’s rate sheet. | Sept 29, 2026 |
VA and FHA Buyers: How Incentives Stack
Builder incentives are still available on government loans, but each program caps what the builder can contribute. Two numbers matter:
- FHA caps seller and builder contributions at 6% of the purchase price. That 6% has to cover the buydown, prepaids, and closing costs together, so a big incentive package can hit the cap quickly.
- VA lets the seller pay normal closing costs, plus up to 4% in concessions for other items. Normal closing costs such as VA-approved fees and discount points are treated separately from additional concessions such as a rate buydown, so the two categories follow different limits. Patrick confirms the exact split on every VA quote before anything is signed.
If you are moving on orders near JBSA, the timing works the same way: incentives sit on top of the financing, but the cap is real, and a quick move-in home often carries the biggest credit because the builder wants it gone. See VA loans for new construction and the PCS to JBSA San Antonio guide for the move-date math.
What You Can Negotiate Beyond the Advertised Offer
The advertised incentive is the starting point, not the ceiling. Lot premiums, design center credits and upgrade pricing, the closing date, and extra incentives on move-in-ready homes that have been sitting are all on the table, and none of them show up in the billboard.
The design center is where buyers overspend, because the markup lives in the options, not the base price. Your agent can push back on upgrade pricing and ask for the allowance or the credit instead of the retail product.
Design center markups add up fast. Let me negotiate them before you sign.
Talk to PatrickAnd remember: the builder contract is written by the builder's attorneys. Your agent reviews it with you before you sign. See what to watch in the 5 contract terms buyers should never agree to.
Don't sign a builder contract nobody on your side has read.
Get My Contract ReviewedDon't Sign With a Builder Until We Talk (The First-Visit Rule)
The sales rep works for the builder. They're friendly and helpful, but they don't represent you, and they can't give you advice the way your agent can.
Most builders only recognize your agent if the agent is with you, or registers you, on your first visit. Walk in alone and sign the guest card, and you may lose the ability to have your own agent with that builder. That one signature often decides who represents you for the whole deal.
Already visited? Call Patrick anyway. If you haven't signed a contract, there may still be options, and it costs nothing to check.
In most cases the builder pays the buyer's agent commission at closing, so the buyer pays nothing out of pocket. You are not choosing between an agent and a discount; you are choosing whether someone on your side reviews the numbers.
CTA #2 · Before Your First Visit
Heading to a Model Home This Weekend? Call Me First.
Most builders only recognize your agent if they're registered on your first visit. If you walk in alone and sign the guest card, you may lose the right to have someone in your corner. Tell me which communities you want to see, and I'll register you before you go.
Free Checklist
Before You Walk Into a Model Home
Print this and keep it on your phone for the visit. Ten items that keep the builder's sales office from becoming the only voice in the room.
- 1Bring your own agent, or have them register you first.
- 2Don't sign the guest card without listing your agent.
- 3Don't sign anything on the first visit.
- 4Get the incentive in writing, with its expiration date.
- 5Ask whether the incentive requires their lender and title company.
- 6Get the builder's Loan Estimate and compare it with an outside quote.
- 7Ask about lot premiums and design center pricing.
- 8Ask about HOA dues and MUD/PID or special district taxes.
- 9Confirm the school district for the exact lot.
- 10Have your agent review the contract before you sign.
Frequently Asked Questions
Is a builder's 3.49% interest rate real?
Yes, the rate is real, but it is usually a temporary buydown, not a permanent one. On a 2-1 buydown you pay 3.49% the first year, 4.49% the second year, and the full note rate from year three on. The fine print and the APR tell you what the loan really costs, so compare the APR and the year-three payment, not just the teaser. The deeper version is in the Ask Patrick answer.
What happens to my payment when a 2-1 buydown ends?
The payment steps up twice: it rises after year one and again after year two, then sits at the full note rate. A 3.49% year-one rate on a 2-1 buydown usually settles around 5.49% from year three on, and the monthly payment can climb by several hundred dollars. Buy a buydown only if your income will cover the step-ups. See the full math in the Ask Patrick answer.
Do I have to use the builder's lender to get the incentives?
No one can force you to use the builder's lender, but most builders tie the advertised incentive to it. You can use your own lender and lose the incentive, or use the builder's lender and compare the whole cost. Sometimes the builder's lender really is the best deal, so line up both Loan Estimates and compare rate, APR, points, fees, credits, and cash to close before you choose. Read the Ask Patrick answer.
Is flex cash better than a lower rate?
It depends on your cash and your plans. Flex cash lowers what you bring to closing, which wins for a buyer who is short on cash to close. A permanent lower rate wins for a buyer who plans to stay long term, because the savings repeat every month for the life of the loan. Compare the five-year cost of each before deciding, and let the calculator above do it for you.
Can I bring my own agent after I already visited a model home?
Most builders only recognize your agent if the agent is with you, or registers you, on your first visit. Walk in alone and sign the guest card, and you may lose the ability to have your own agent with that builder. If you already visited, call Patrick anyway: if you have not signed a contract, there may still be options. Read the Ask Patrick answer.
Does the builder pay my buyer's agent?
In most cases yes. The builder pays the buyer agent commission at closing, so the buyer pays nothing out of pocket for representation. That is why you should have your own agent from the first visit: representation that costs you nothing, and someone reviewing the contract and the incentives on your side.
Can I use builder incentives with a VA or FHA loan?
Yes, but each program caps what the builder can contribute. FHA limits seller and builder contributions to 6% of the purchase price. VA lets the seller pay normal closing costs, plus up to 4% in additional concessions. A big incentive package can hit those caps, so confirm the program limits on your quote before you rely on the number.
Builders have their own agent. You should too.
The builder has a sales team, a lender, a title company and a contract written by their attorneys. You get one person working only for you. I handle the real estate and the mortgage myself, so I can see the whole deal: the price, the incentives, the rate and the fine print. And it costs you nothing out of pocket.
Patrick, The Mortgage Patriot
More Ways to Start
Patrick Kevin Fagan
Texas Real Estate Sales Agent #454749, AXEN Realty LLC · Senior Loan Officer, NMLS ID #877741, NEXA Mortgage, LLC (NMLS #1660690)
Patrick Kevin Fagan is a dual-licensed REALTOR and mortgage loan officer with 23+ years in loan origination and 19 years in real estate, helping first-time homebuyers, growing families, sellers, and investors across Greater San Antonio and the Texas Hill Country. He educates buyers on YouTube so they can lower their rate, minimize cash to close, and use down payment assistance programs.
Related Reading
Interest Rate Buydowns Explained: 2-1, 3-2-1 and 1-0
How the step-down math works
Seller Concessions: How Much by Loan Type
FHA, VA and conventional caps
Closing Costs in Texas: What Buyers Pay
What the credit actually covers
Buying New Construction in San Antonio: Incentives and Fine Print
Base price vs finished price
New Construction vs Resale in San Antonio
Which route fits your numbers
Builder's Lender vs Your Own Lender
The four-sided comparison
Ask Patrick: Builder Incentive Questions
Equal Housing Opportunity
Patrick Kevin Fagan, NMLS ID #877741 · NEXA Mortgage, LLC, NMLS #1660690 · Texas Real Estate Sales Agent #454749, AXEN Realty LLC, 1399 Frontier, Spring Branch, TX 78070.
Rates, APRs, and incentives in this article were advertised by the builders as of September 29, 2026, and change without notice. Every rate shown includes its advertised APR and key assumptions where the builder published them. Payment examples are illustrative, principal and interest only, and are not loan offers. Mortgage originations are available statewide across Texas; real estate services are provided in Greater San Antonio and the Texas Hill Country. The Texas Real Estate Commission Consumer Protection Notice and Information About Brokerage Services links are in the site footer.
This page was updated Updated September 29, 2026. Incentive tables are refreshed at least monthly and at every quarter end.
Answered by Patrick Kevin Fagan
Texas Real Estate Sales Agent #454749, AXEN Realty LLC · Senior Loan Officer, NMLS ID #877741, NEXA Mortgage, LLC
Call or text: 210-317-6514
