
Patrick's Quick Answer
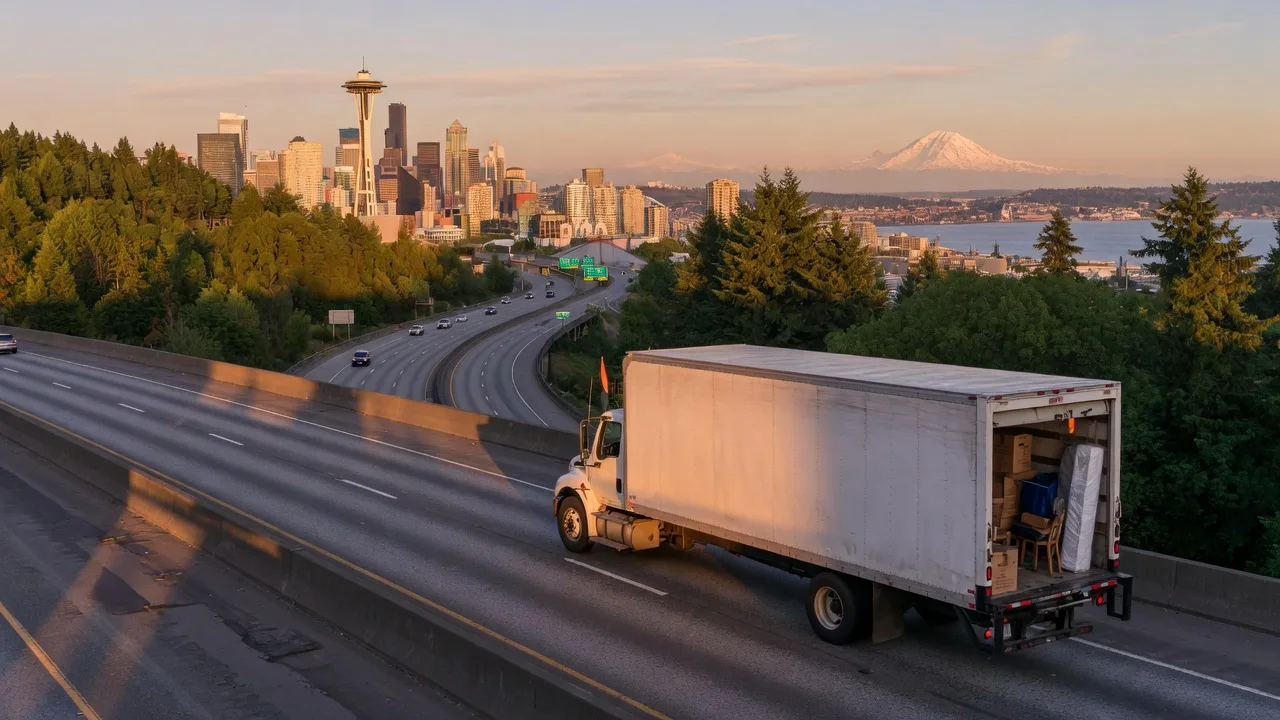
Moving from Seattle to San Antonio is a no-income-tax to no-income-tax move with the biggest price gap since the California cities in this series. The Seattle city median home sale price sits near $874,000 while the San Antonio city median sits near $257,000 (Redfin, three months to August and September 2026), roughly a 3.4-to-one gap. Washington pairs its missing income tax with a 0.58% WA Cares payroll tax on all wages and a capital gains tax on high earners, taxes Texas does not have, and the sales tax drops from 10.55% in Seattle to 8.25% in San Antonio. The honest trade is the usual Texas one: property tax rates run higher than King County's, the summer is long and hot instead of mild and gray, and rain arrives on about half as many days. Rate and price are separate inputs, so the complete monthly payment, not the price tag, is what you compare.
I work this move from both ends: I originate home loans statewide across Texas, including for Washington buyers moving here, and I sell real estate around Greater San Antonio, so Seattle clients get the financing and the contract side coordinated in one plan. This post is the Seattle city-level comparison, with the numbers dated and the sources named. The deeper relocation playbook, with the corridor comparisons and blank payment worksheets, is in the relocation hub.
Why this particular move keeps happening
Washington to Texas is one of the busiest cross-country corridors in the country. In the most recent IRS migration data, 2022 to 2023, about 53,900 households moved from Washington to Texas, which made Texas the number two out-of-state destination for Washington movers behind California (IRS SOI migration data, as compiled by migration trackers; the IRS counts returns, meaning households, not individual people). The reasons travel in a familiar order: a median home in Seattle costs about 3.4 times its San Antonio counterpart, a combined sales tax near the top of any big American city, gray winters, and a tech-heavy economy where a growing share of households can do their job from anywhere.
San Antonio answers with the same tradeoffs the rest of this series documents: a median home that costs a fraction as much, no income tax, a lower combined sales tax, and a job base built on military, healthcare, and financial services, in exchange for higher property tax rates, hot humid summers, and a commute culture that assumes you drive. Neither city is better; they answer different questions. Because the price gap here lands close to the California moves covered earlier in this series, the down payment line and the complete payment carry most of the story, and this post is built around that.
The two markets, side by side
City-level figures from the same tracker put this pairing in perspective: Seattle's median runs about 3.4 times San Antonio's, the largest gap in the series since Los Angeles and San Diego. One honest caveat before the table: Seattle's city median blends a condo-heavy inventory near the water and downtown with vintage single-family blocks in the neighborhoods, so $874,000 buys very different property types depending on where you look, and the San Antonio median points more consistently at a single-family house:
| Metric and period | Seattle | San Antonio |
|---|---|---|
| City median home sale price (Redfin, three months to Aug/Sept 2026) | about $874,000, down about 2.8% year over year | about $257,000, down about 2.9% year over year |
| Ratio of city medians | baseline | about 3.4-to-one cheaper |
| Broader county median, same window | trackers differ on a metro with many condos and townhomes; the city figure is the consistent read here | about $299,275 (Bexar County, SABOR August 2026) |
| 20% down payment on the city median | about $174,800 | about $51,400 |
| Cost of living index, U.S. average baseline 100 (BestPlaces) | about 158.1, roughly 42% to 46% higher than San Antonio | about 91.3 |
| State individual income tax | none, paired with the WA Cares payroll tax | none |
Two honest caveats. First, a city median hides a wide range of neighborhoods in both places, and Seattle spans everything from downtown condos to Queen Anne craftsman bungalows, so treat these figures as orientation, not a shopping list. Second, different trackers measure differently: Zillow tracks average home value rather than median sale price, and the Seattle Redfin figure was updated about a month before the San Antonio figure, so the two snapshots do not cover identical weeks. The gap to San Antonio is clear under every method; the exact size depends on which definition you use.
Cost of living: Seattle is the most expensive origin in this series
BestPlaces puts Seattle about 58% above the national average (index 158.1) and San Antonio about 9% below it (index 91.3), and the direct comparison lands San Antonio roughly 42% to 46% less expensive. Housing is the dominant driver: BestPlaces scores Seattle's homeowner housing index near 309 versus about 76 in San Antonio. Rents tell the same story, about two to one. Groceries run higher in Seattle as well, close to 9% above the national average versus about 9% below in San Antonio:
| Cost of living line (2026 trackers) | Seattle | San Antonio |
|---|---|---|
| Overall index, U.S. average baseline 100 (BestPlaces) | about 158.1, roughly 42% to 46% higher than San Antonio | about 91.3 |
| Typical 1-bedroom rent (Apartment List, Oct 2026 Seattle / Sept 2026 San Antonio) | about $1,948 a month | about $960 a month |
| Typical 2-bedroom rent (Apartment List, same period) | about $2,432 a month | about $1,182 a month |
| Groceries and restaurants | roughly 9% above the national average on groceries | roughly 9% below the national average on groceries |
| Utilities | mild heating load, cheap hydropower, low cooling load | long summer cooling load drives the bill |
| Combined sales tax | 10.55% | 8.25% |
Seattle's cheap hydropower keeps electric bills modest by national standards, but the city's overall cost structure is simply high. On the same $110,000 gross household income, a Seattle paycheck also carries the 0.58% WA Cares payroll tax, about $638 a year, roughly $53 a month, a line that disappears entirely in Texas. That is a unique Washington cost, and it belongs in every honest Seattle-to-Texas budget.
Income tax: the only no-income-tax to no-income-tax pairing in the series
Every other pairing so far moved from an income-tax state to a no-income-tax state, so the state income tax line was the headline of the savings story. This move is different: Washington and Texas both have no individual income tax, so that line is a straight tie, the first one in the series. The honest version of this move is that Washington collects its revenue in other places, and a few of those places travel badly:
- WA Cares long-term care payroll tax. Washington is the only state with a mandatory public long-term care payroll tax, 0.58% of all wages with no salary cap. A $110,000 household pays about $638 a year into it. Texas has no equivalent line.
- Capital gains tax. Washington taxes long-term capital gains at 7% above a standard deduction (about $278,000 for 2025), with an additional rate on gains over $1 million. Real estate sales are exempt, but investment sales are not. Texas has no capital gains tax.
- Seattle's payroll expense tax. Seattle's JumpStart tax applies to large employers' payroll, which is invisible on your W-2 but a real factor in the city's cost structure and in what employers there factor into salary.
- Sales tax above 10%. Seattle's combined 10.55% rate is among the highest in the country; San Antonio's 8.25% is high for Texas but over two points lower. On a $50,000 car, that is about $1,150 of difference.
The net read for a working family: the income tax line saves nothing because both states are at zero, but the payroll tax line and the sales tax line usually net in San Antonio's favor, and the housing line dominates both. What the move does not do is hand a Seattle household a state income tax refund for the trouble, so plan the budget around the complete payment, not the tax line.
Property taxes: lower rate, but on a much higher price
King County's effective property tax rate is modest, about 0.92% of value for a typical Seattle home, but the median home price is so high that the median dollar bill lands near $8,000 a year. Bexar County's median effective rate runs about 1.55%, and a typical combined in-city San Antonio rate lands near 2.27% of taxable value, but on a $257,000 median home the annual bill lands closer to $4,000. Same rates debate, opposite dollar answer:
| Property tax line (2026 sources) | Seattle / King County | San Antonio / Bexar County |
|---|---|---|
| Effective tax rate on value | about 0.92% (King County) | about 1.55% median effective; about 2.27% combined in-city rate on taxable value |
| Estimated annual bill on a median-priced home | about $8,000 on $874,000 | about $4,000 on $257,000 |
| How value is set | annual revaluation near market, with a 1% annual levy-lid cap on each district's total collection | appraisal district sets values each January, with district rates applied on top |
| Owner protections | levy lid limits district growth; voter-approved lid lifts can raise it | 10% annual homestead appraisal cap, homestead exemption filed after closing, annual protest window |
Two notes worth keeping. Washington's 1% levy lid caps how much each taxing district can collect, not what an individual bill does when values rise unevenly, so a fast-appreciating Seattle home can still see a big bill. Texas protects the primary residence specifically: the homestead exemption removes part of the value from school district taxation, the appraisal cap holds annual growth to 10%, and both require filing, with timing that matters for your first year. The property taxes in San Antonio explainer and the homestead exemption guide cover the filing steps, and the exact address, district, and exemptions decide the real number in either county.
Selling in Seattle before you buy in San Antonio
Seattle sellers carry a closing cost that Texas sellers never see: the real estate excise tax, called REET, which is paid by the seller at closing. Washington's state REET is graduated, 1.10% on the first $525,000 and 1.28% on the next bracket, and Seattle adds a flat local REET of 0.50% on the full sale price. On a median-priced $874,000 Seattle home, that works out to roughly $10,200 in state REET and about $4,370 in Seattle's local REET, about $14,600 of seller-side excise tax in total. Texas has no state transfer tax for either side, one of about 13 states without one, so the same sale in San Antonio carries no excise tax line at all.
The rest of the proceeds math runs through the same federal machinery in both states: the primary-residence capital gains exclusion of $250,000 for single filers and $500,000 for married filing jointly applies to the sale in either state, Washington's capital gains tax explicitly exempts real estate, and Texas has no state capital gains tax. What changes is the shape of the closing statement: Seattle's sale has the REET lines, Texas's purchase has the buyer-side title insurance and lender fees, and prorated property taxes in both. The cash to close explainer and the closing costs in Texas guide show where the money lands on the Texas side, and a qualified tax professional should confirm the sale side, since nothing here is tax advice.
The monthly payment: same budget, both cities
Price is not payment. These are illustrative numbers, dated October 2026, run on the series' standard assumption set: a 30-year fixed mortgage at 6.5%, 20% down, principal and interest plus an annual property tax estimate at each area's effective rate, with no insurance, HOA, or mortgage insurance included. They exist to compare the two cities on the same math, not to quote a rate or approve a loan:
| Illustrative line, dated Oct 2026 | Seattle median | San Antonio median |
|---|---|---|
| Home price | $874,000 | $257,000 |
| 20% down payment | $174,800 | $51,400 |
| Loan amount | $699,200 | $205,600 |
| Principal and interest at 6.5%, 30-year fixed | about $4,420 a month | about $1,300 a month |
| Property tax at each area's effective rate | about $670 a month | about $330 a month |
| Estimated complete P&I + tax payment | about $5,090 a month | about $1,630 a month |
That is roughly a three-to-one payment gap. The flip side is what the same budget buys: a household carrying the Seattle median payment of about $5,090 a month, run through the same assumptions in San Antonio's tax environment, can support about an $800,000 home, roughly 3.1 times the San Antonio median. That is the single most useful number in this whole comparison, and it is why the local version of this move usually goes: sell in Seattle, buy in San Antonio, bank the payment difference or buy more house on the same payment.
Cash to close: what actually changes hands in Texas
The down payment is not the whole cash number, and Texas shapes the rest of it differently than Washington. On a Texas purchase, cash to close includes the down payment plus title insurance (an owner's policy is a real and expected line, with the lender's policy on top), lender origination and third-party fees, and prepaids for property taxes and homeowners insurance at closing. The state adds no transfer tax, and many buyers negotiate a seller credit toward these costs. On the Seattle side, the sale proceeds are net of the REET described above, so the cash that actually arrives in Texas is typically larger than a first glance at the sale price suggests.
The timing works in your favor if you plan it: a Seattle sale and a San Antonio purchase can run on overlapping calendars, and the Texas contract's option period gives a buyer from out of town a defined window to do the inspections and the verifying that video tours cannot. The pre-approval before you fly is the step that makes every other step faster, and pre-approval from a Texas lender who works with out-of-state buyers means the relocation deadline does not become a fire drill.
Climate: two kinds of gray
This pairing trades the most consistent rain for the most consistent heat. Seattle records about 155 to 156 days a year with measurable precipitation and about 38 inches of rain; San Antonio records about 81 wet days and about 33 inches. Seattle's July high runs about 76 degrees and its January low about 37; San Antonio's July and August highs run about 94 to 95 degrees and its January low is about 41. Snow tells the sharpest story: Seattle averages about 5 to 6 inches a year, and San Antonio about 0.2 inches, a trace that melts by midday.
There is one house-level difference that surprises Seattle buyers more than the temperature. Because the Pacific Northwest's summers were historically mild, many older Seattle homes were built without central air conditioning and without ductwork, and the metro only passed a majority of homes with any cooling in recent years. Texas homes assume central AC as the default, and the long cooling season is a real utility line. Seattle's light snow and heavy rain become San Antonio's long summer, and the flood zone check at the exact address belongs in every Texas diligence list, same as it does in Washington.
Seattle house habits that reset on arrival
A few Seattle assumptions need adjusting on arrival, and they show up more than you might think:
- The air conditioning question reverses. In Seattle the house-hunting question is "does it have AC?" In San Antonio it is "how old is the AC, and does the system cover the whole house?" Budget for the cooling season and check the system age at inspection.
- The basement disappears. Many older Seattle homes sit on daylight basements or crawl spaces, and storage lives underground. Texas homes are overwhelmingly slab on grade, so attic space, garage, and closets carry the storage, and the utility rooms are laid out differently. Plan the move of the basement stuff.
- The lot math changes. Seattle's median lot is small enough that a two-car garage is a feature and a yard is a luxury. The San Antonio median is a house on a lot, so budget for yard maintenance and, in the Hill Country corridors, well and septic on unincorporated land.
- The water bill flips. Seattle's abundant hydropower and rainfall keep water cheap and electric bills modest. San Antonio's summer irrigation and cooling load are the expensive months, so a sprinkler system and a pool both belong in the utility math.
- The transit habit ends. Thousands of Seattleites live with one car or none, riding light rail, buses, and ferries. San Antonio is a driving city, and the honest planning step is to test the commute and count the cars before you commit to a corridor.
- The two-hour clock is real. Seattle runs Pacific Time and San Antonio runs Central, so the move gains two hours of daylight scheduling, and family video calls with Seattle need a new rhythm.
- The perpetual-gray trade is a budget item, not just a mood. Fewer than half as many wet days, but a much longer cooling season, so the wardrobe and the utility budget trade places on the calendar.
The trip: four hours by air, three days by truck
Seattle to San Antonio is about 2,146 miles by road, most commonly on I-5 to California for the southern route or I-84 and I-40 through the desert states, and nonstop driving time is roughly 32 to 33 hours. With stops and a night or two in motels, most families plan the drive as three days, which is how a moving truck plus a second vehicle usually travel. By air the same trip is about 1,770 miles along the great circle, and nonstop flights between Seattle-Tacoma International and San Antonio International run about four hours on Alaska Airlines, with connections on other carriers (verify current schedules and times).
This is a fly-to-visit distance, not a weekend drive: house-hunting trips, inspection windows, and closing day are flight decisions, and they work best with pre-approval already in hand. A pod-and-flight move with a short overlap on rent is the common pattern: ship the household goods, fly down for the option period and inspection, close, and let the truck arrive on its own schedule. For remote and hybrid workers the move is simpler than it was a decade ago, but the honest planning step is the same for any distance move: verify financing first, shortlist on video, and let the Texas option period plus a local inspection do the verifying that video cannot.
The military move: JBLM to JBSA
For service members this is one of the cleaner corridors in the country. Joint Base Lewis-McChord, about 35 miles south of Seattle near Tacoma, is one of the Army's largest installations, and Joint Base San Antonio combines Lackland, Randolph, and Fort Sam Houston (the military's Medical Education and Training Campus) plus Camp Bullis, so orders between the two stations are routine, especially along the medical and training pipelines. PCS timing follows the orders cycle, and the practical question is always the same: what does the housing allowance buy at each station?
| 2026 BAH, E-5 with dependents | Rate | Share of the local median payment |
|---|---|---|
| Seattle military housing area (MHA WA309) | about $3,135 a month | about 62% of the Seattle median payment |
| Tacoma / JBLM (MHA WA311) | about $2,556 a month | a JBLM-area home runs below the Seattle figure; the practical share depends on where in the metro the family buys |
| San Antonio (MHA TX285, JBSA) | about $1,869 a month | about 115% of the San Antonio median payment |
That table is illustrative arithmetic with a stated assumption set, not a promise, and every service member's file differs by rank, dependency status, and the specific home. The honest read: the BAH number drops by roughly a third between the two areas, but the median home payment drops more, so the allowance covers a larger share of a median-priced home in San Antonio. The military families I work with from this corridor most often land on the northeast side, in the Cibolo, Schertz, and New Braunfels corridor toward Randolph and along I-35.
The VA loan itself works the same in both states: 0% down, no monthly mortgage insurance, and a one-time funding fee that runs about 2.15% of the loan for first-time use with less than 5% down (about 3.30% for subsequent use), with the fee waived for veterans receiving VA disability compensation. VA financing is a specialty of mine, and the VA loans for JBSA buyers guide, the best towns per base guide, and the orders-to-keys PCS guide cover the timing, the paperwork, and the corridor comparisons.
Where you land in San Antonio
Seattle transplants land all over the San Antonio area, and the honest answer is that the right corridor depends on your commute, your budget, and the property type you want. This market splits into a few corridors, each with a full guide in our community library:
- I-35 northeast, Schertz, Cibolo, and New Braunfels: town and suburban homes with city services, the fastest-growing family corridor in the area and a short highway hop to downtown and Randolph, which makes it the default for military families. New Braunfels guide.
- US-281 north, Bulverde and Spring Branch: larger lots and Hill Country terrain, with much of the corridor unincorporated, so wells, septic, and utility districts are common. Bulverde guide.
- I-10 west, Boerne and Fair Oaks Ranch: a town with its own services plus master-planned communities that cross Kendall, Bexar, and Comal County lines. Boerne guide.
- Canyon Lake: lake-country acreage and resort-style communities in unincorporated Comal County, quiet and spread out rather than walkable. Canyon Lake guide.
Seattle buyers also notice one thing a condo-and-small-lot city market rarely offers: choices with meaningful lot sizes at a fraction of the Seattle price per home. Each corridor carries its own county, school district, appraisal district, utility mix, and tax jurisdictions, so the comparison is never "metro versus metro" but "exact address versus exact address." The relocation hub compares all the corridors on the complete monthly payment without declaring a universal winner, because there is not one.
Questions buyers ask before this move
Does Washington state really have no income tax, like Texas? Tap to expand
Are property taxes really higher in Texas even though homes cost less? Tap to expand
How much does the sales tax difference actually matter? Tap to expand
Is Seattle to San Antonio a common military move? Tap to expand
Making the move? Let's put the numbers on paper.
I work the financing and the real estate side of the same move, so the price, the Texas tax load, the insurance question, the cash to close, and the offer strategy get coordinated in one plan. Bring your Seattle numbers, sale proceeds or not, and I will show you what they do in San Antonio.
A buyer who went through the process put it this way: "He's very responsive, professional, and will clearly explain every step of your buying process, and best of all he was able to keep some money in my pocket." More client words are on the reviews page.
About Patrick Kevin Fagan, REALTOR®
Patrick Kevin Fagan is a Texas Real Estate Sales Agent (#454749) with AXEN Realty LLC and a Senior Loan Officer (NMLS ID #877741) with NEXA Lending. He brings 23+ years in mortgage lending and 19 years in real estate, serving homebuyers, homeowners, and sellers across Greater San Antonio and the Texas Hill Country, and originates home loans statewide across Texas, including for Washington buyers moving in. VA financing is a specialty, and the deeper relocation playbook, with the migration data and blank payment worksheets, is in the relocation hub.
Sincerely, Patrick Kevin Fagan
Answered by Patrick Kevin Fagan
Texas Real Estate Sales Agent #454749, AXEN Realty LLC · Senior Loan Officer, NMLS ID #877741, NEXA Mortgage, LLC
Call or text: 210-317-6514
Updated October 16, 2026. Median price, cost of living, income tax, payroll tax, sales tax, property tax, REET, BAH, and climate figures are dated, single-tracker snapshots (sources named in the post) and are directional, not forecasts or quotes. Payment math is illustrative arithmetic for comparison using a stated assumption set, never a rate quote or an approval. BAH figures are official 2026 rates; what they cover depends on the specific home and the complete payment. Washington and Texas tax treatment of a home sale is a qualified tax professional's question. Verify the appraisal district record, tax rates, insurance quotes, utility types, HOA documents, AC age, and school district for the exact address before you commit. Nothing here is neighborhood steering or a claim that any area is better for any person or group; area fit is personal, and fair housing law applies to every inquiry.
