
Your Texas Mortgage Loan Officer, On Your Side
I am Patrick Kevin Fagan, a mortgage loan officer with NEXA Mortgage, LLC dba NEXA Lending and a Texas real estate sales agent with AXEN Realty LLC. I originate home financing across the state of Texas and focus my real estate work on Greater San Antonio and the Texas Hill Country, where I help first-time buyers, growing families, veterans, and investors get clear financing and close with confidence.
Because I am licensed on both sides of the transaction, I can structure offers that get accepted and financing that minimizes your cash to close. That dual license is the reason clients call me for mortgage help first.
Who I Help
Mortgage Help for Every Stage of Homeownership
Whether you are buying your first home, moving up, relocating to San Antonio, or investing, I explain the loan options in plain English and build a financing plan around your numbers.
First-Time Buyers
I explain every stage from pre-approval to keys, so the process never feels like a mystery.
Growing Families
More space means a bigger loan structure. I help growing families find financing that protects the budget.
Military and Veterans
VA loan expertise and PCS support for the San Antonio military community, from eligibility to close.
New Construction
Builder contracts, incentives, and construction-friendly financing handled as one conversation.
Investors
Financing solutions for rental properties and portfolio growth across Texas.
Sellers
I work with sellers on pricing and negotiation strategy while helping their buyers get clear financing.
The Dual-License Advantage
A Loan Officer Who Also Holds a Real Estate Sales License
Most buyers work with two separate professionals who rarely talk to each other. On my side, the mortgage and the offer are one conversation. I structure purchase offers that appraise, underwrite, and close, and I design the financing to fit the offer.
My mortgage license is issued under NEXA Mortgage, LLC dba NEXA Lending (Company NMLS 1660690); my individual NMLS is 877741. My Texas real estate sales license (#454749) is held with AXEN Realty LLC. I originate loans statewide and serve clients face to face across Greater San Antonio and the Texas Hill Country.
Lower Cash to Close
Down payment assistance, seller concessions, and loan structure used together to shrink what you bring to the table.
Stronger Offers
Offers backed by a pre-approval from the same professional who will underwrite and close the loan.
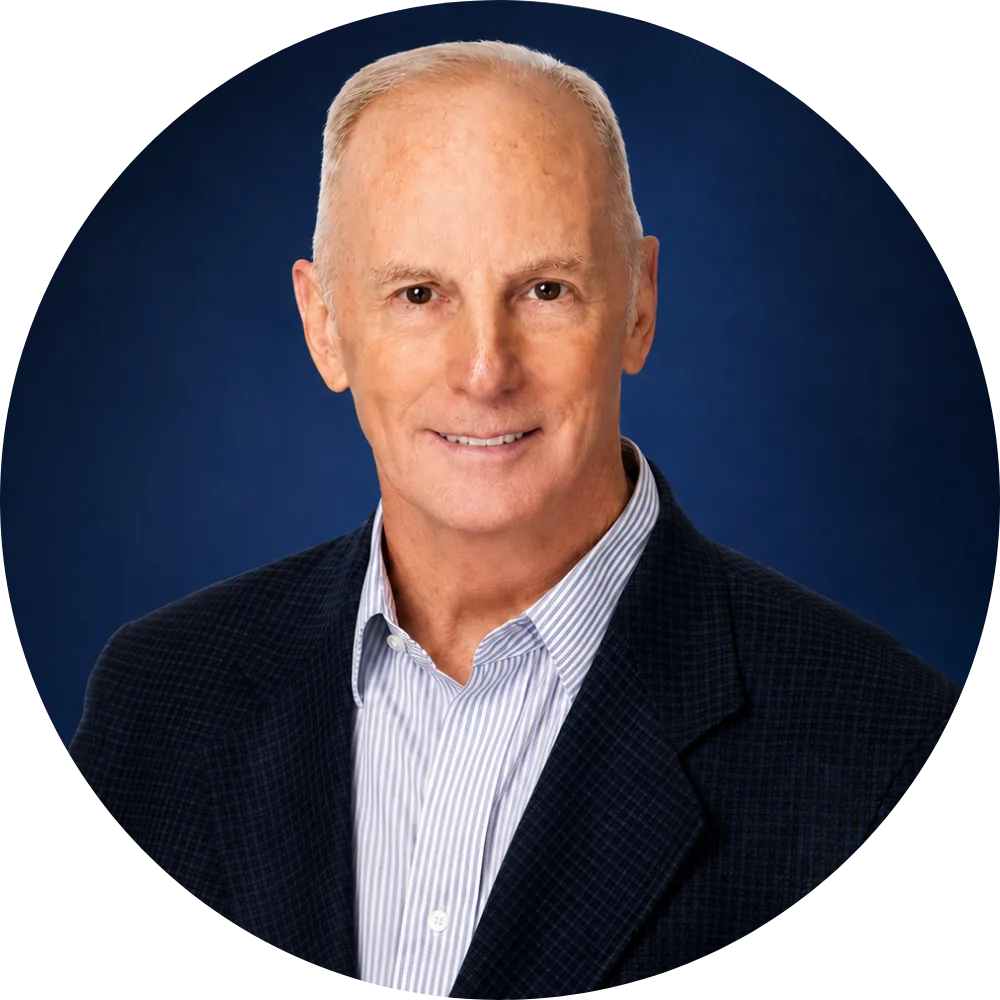
Patrick's Take
“My job is to replace uncertainty with confidence. I explain every step, protect your interests, and keep your money in your pocket whenever the rules allow it. You are never on your own with me.”
Patrick Kevin Fagan
Mortgage Loan Officer and REALTOR
Where I Lend
Statewide Origination, Local Expertise on the Ground
I originate home financing across the state of Texas. My real estate work is concentrated in Greater San Antonio and the Texas Hill Country, so my mortgage advice is grounded in the neighborhoods where you are actually buying.
San Antonio Mortgage Loan Officer
Mortgage lending built on local market knowledge plus a Texas real estate sales license.
Spring Branch TX Mortgage Loan Officer
Hill Country acreage, wells and septic, and USDA-friendly lending around Spring Branch.
Bulverde TX Mortgage Loan Officer
New construction and resale financing across Bulverde and the US-281 corridor.
New Braunfels Mortgage Loan Officer
Comal County and the I-35 corridor, from Gruene to the newest master-planned sections.
Boerne Mortgage Loan Officer
Kendall County Hill Country homes, from Main Street to new construction and acreage.
Schertz Mortgage Loan Officer
I-35 and FM 3009 financing near JBSA-Randolph for military and first-time buyers.
Cibolo Mortgage Loan Officer
Guadalupe County growth corridor with new construction and USDA-eligible pockets.
Fair Oaks Ranch Mortgage Loan Officer
Gated Hill Country communities at the Bexar, Kendall, and Comal county line.
North San Antonio Mortgage Loan Officer
The 1604 and 281 corridor, from Stone Oak to Rogers Ranch and beyond.
Stone Oak Mortgage Loan Officer
Master-planned communities off Loop 1604 with HOA-aware financing.
Helotes Mortgage Loan Officer
The 16 and 211 corridor where Hill Country feel meets Bexar County practicality.
Mortgage Loan Officer in Austin
Statewide Texas mortgage origination with a first-time homebuyer focus for Austin buyers.
Mortgage Loan Officer in Houston
Statewide Texas mortgage origination with a first-time homebuyer focus for Houston buyers.
Mortgage Loan Officer in Dallas-Fort Worth
Statewide Texas mortgage origination with a first-time homebuyer focus for DFW buyers.
VA Loans in Texas
Eligibility, benefits, funding fee, and the road from pre-approval to closing for veterans.
Texas Down Payment Assistance
Grants, forgiven loans, and lower cash-to-close strategies for Texas buyers.
Mortgages and Financing Q&A
Over 120 mortgage questions answered in plain language, from rates and buydowns to credit and closing costs.
Start Reading
Mortgage Guides Written by Patrick Kevin Fagan
How to Choose a Mortgage Lender in San Antonio
Local Lender vs Big Bank vs Online Lender
How Mortgage Rates and Loan Types Work
Why Your Real Estate Agent Is Not Your Mortgage Guy
One Professional for Both: Mortgage and Real Estate
The Best First-Time Homebuyer Loans in Texas
How to Get Pre-Approved
Mortgage and Financing Question Library
Ready to talk about your loan?
Book a free discovery call and we will map out your loan options, down payment assistance, and a realistic cash-to-close number. If you prefer, call or text me directly at 210-317-6514.
Loan Estimate FAQ
How to pick the lender that fits you
Who is the best mortgage lender in San Antonio right now? Tap to expand
What should a complete lender comparison include? Tap to expand
Is there any way to check eligibility without taking a credit hit or going through a specific lender? Tap to expand
Patrick's Quick Answer: for some programs, yes. The USDA single-family eligibility screen is public and runs on address and household size, before any lender application and before any credit pull. A real loan still goes through lender underwriting and a credit inquiry at application, and a passing screen is not an approval.
- The public screen comes first: the USDA eligibility map at eligibility.sc.egov.usda.gov lets you enter the property address and household details to see whether the area and income picture may qualify for a USDA loan. It does not ask for your credit and it is not a mortgage application with any lender.
- What still requires a lender: income and debt underwriting, the credit history review, the property appraisal, and the full loan file all belong to the lender, and a formal application typically includes a credit inquiry. A quick pre-quote conversation can often happen without a hard pull, so ask which stage you are at before you apply.
- No promise: passing the public address and household screen never equals approval. Approval still depends on credit, debt-to-income, property eligibility, and the complete underwriting picture, which is exactly what a loan officer works through with you.
This question is also answered in the Ask Patrick library.
