
The standard answer to "which loan should a first-time buyer use" is FHA, and the standard reason is the 3.5% down payment. Then the closing table shows the rest of the bill: closing costs on top of the down payment, a number big enough to knock buyers out of the market. Down payment assistance bolts onto an FHA loan to attack exactly that number. Here is why the pairing works, what the structure looks like, and the honest monthly math behind it.
Quick Answer
Yes, DPA works with FHA in Texas, and it is the most common pairing in the state. FHA's 3.5% down plus a DPA second lien plus seller concessions can turn a cash need of roughly $18,900 into roughly $1,000 out of pocket on the right file. FHA brings the 580/3.5% entry, the DPA program brings its own credit and income gate, and the total payment, second lien and all, is what decides if the combo is right.
Get help lowering your cash to close with DPA on an FHA loan.
Why FHA and DPA pair so often
FHA was built for buyers with less cash and flexible credit, and DPA is built for the same buyer, which is why the two keep ending up in the same contract. FHA's standard entry is 3.5% down, and the down payment plus typical closing costs on a first home adds up fast: a cash need in the range of $18,900 on a typical purchase. DPA attacks the down payment, seller concessions attack the closing costs, and the buyer's own cash collapses.
The approved shape of the deal: a first-time buyer on a $300,000-style purchase structures the FHA first mortgage with 3.5% down, layers a DPA second lien over the down payment, and negotiates seller concessions toward closing. The result is a closing check around $1,000 out of pocket on a home they own.
Real-world consequence: that number changes the entire conversation. A buyer who was months away from saving a full down payment is buying now, on a first mortgage and a second lien, with their own cash intact for the moving van.
How the structure works: FHA first, DPA second, concessions
The stack has three pieces and an order. First comes the FHA first mortgage, the loan that actually buys the house. Second comes the DPA second lien, recorded behind the first mortgage, which is why the program allows second liens and why the lender has to approve the arrangement in advance. Third come the seller concessions, negotiated into the contract and used at closing to absorb costs the assistance does not cover.
Nothing about the stack removes the qualification for the FHA mortgage. The buyer still needs income, debt, credit, an appraisal, and a property that meets FHA standards. What the stack removes is the cash, and the cash is the part most first-time buyers cannot manufacture.
The requirements: FHA's 580/3.5% entry and DPA's gate
Two gates stack just like the loans do. FHA's standard door is a credit score around 580 with 3.5% down, and buyers scoring 500 to 579 generally need a larger down payment to qualify at all. That is the loan's gate.
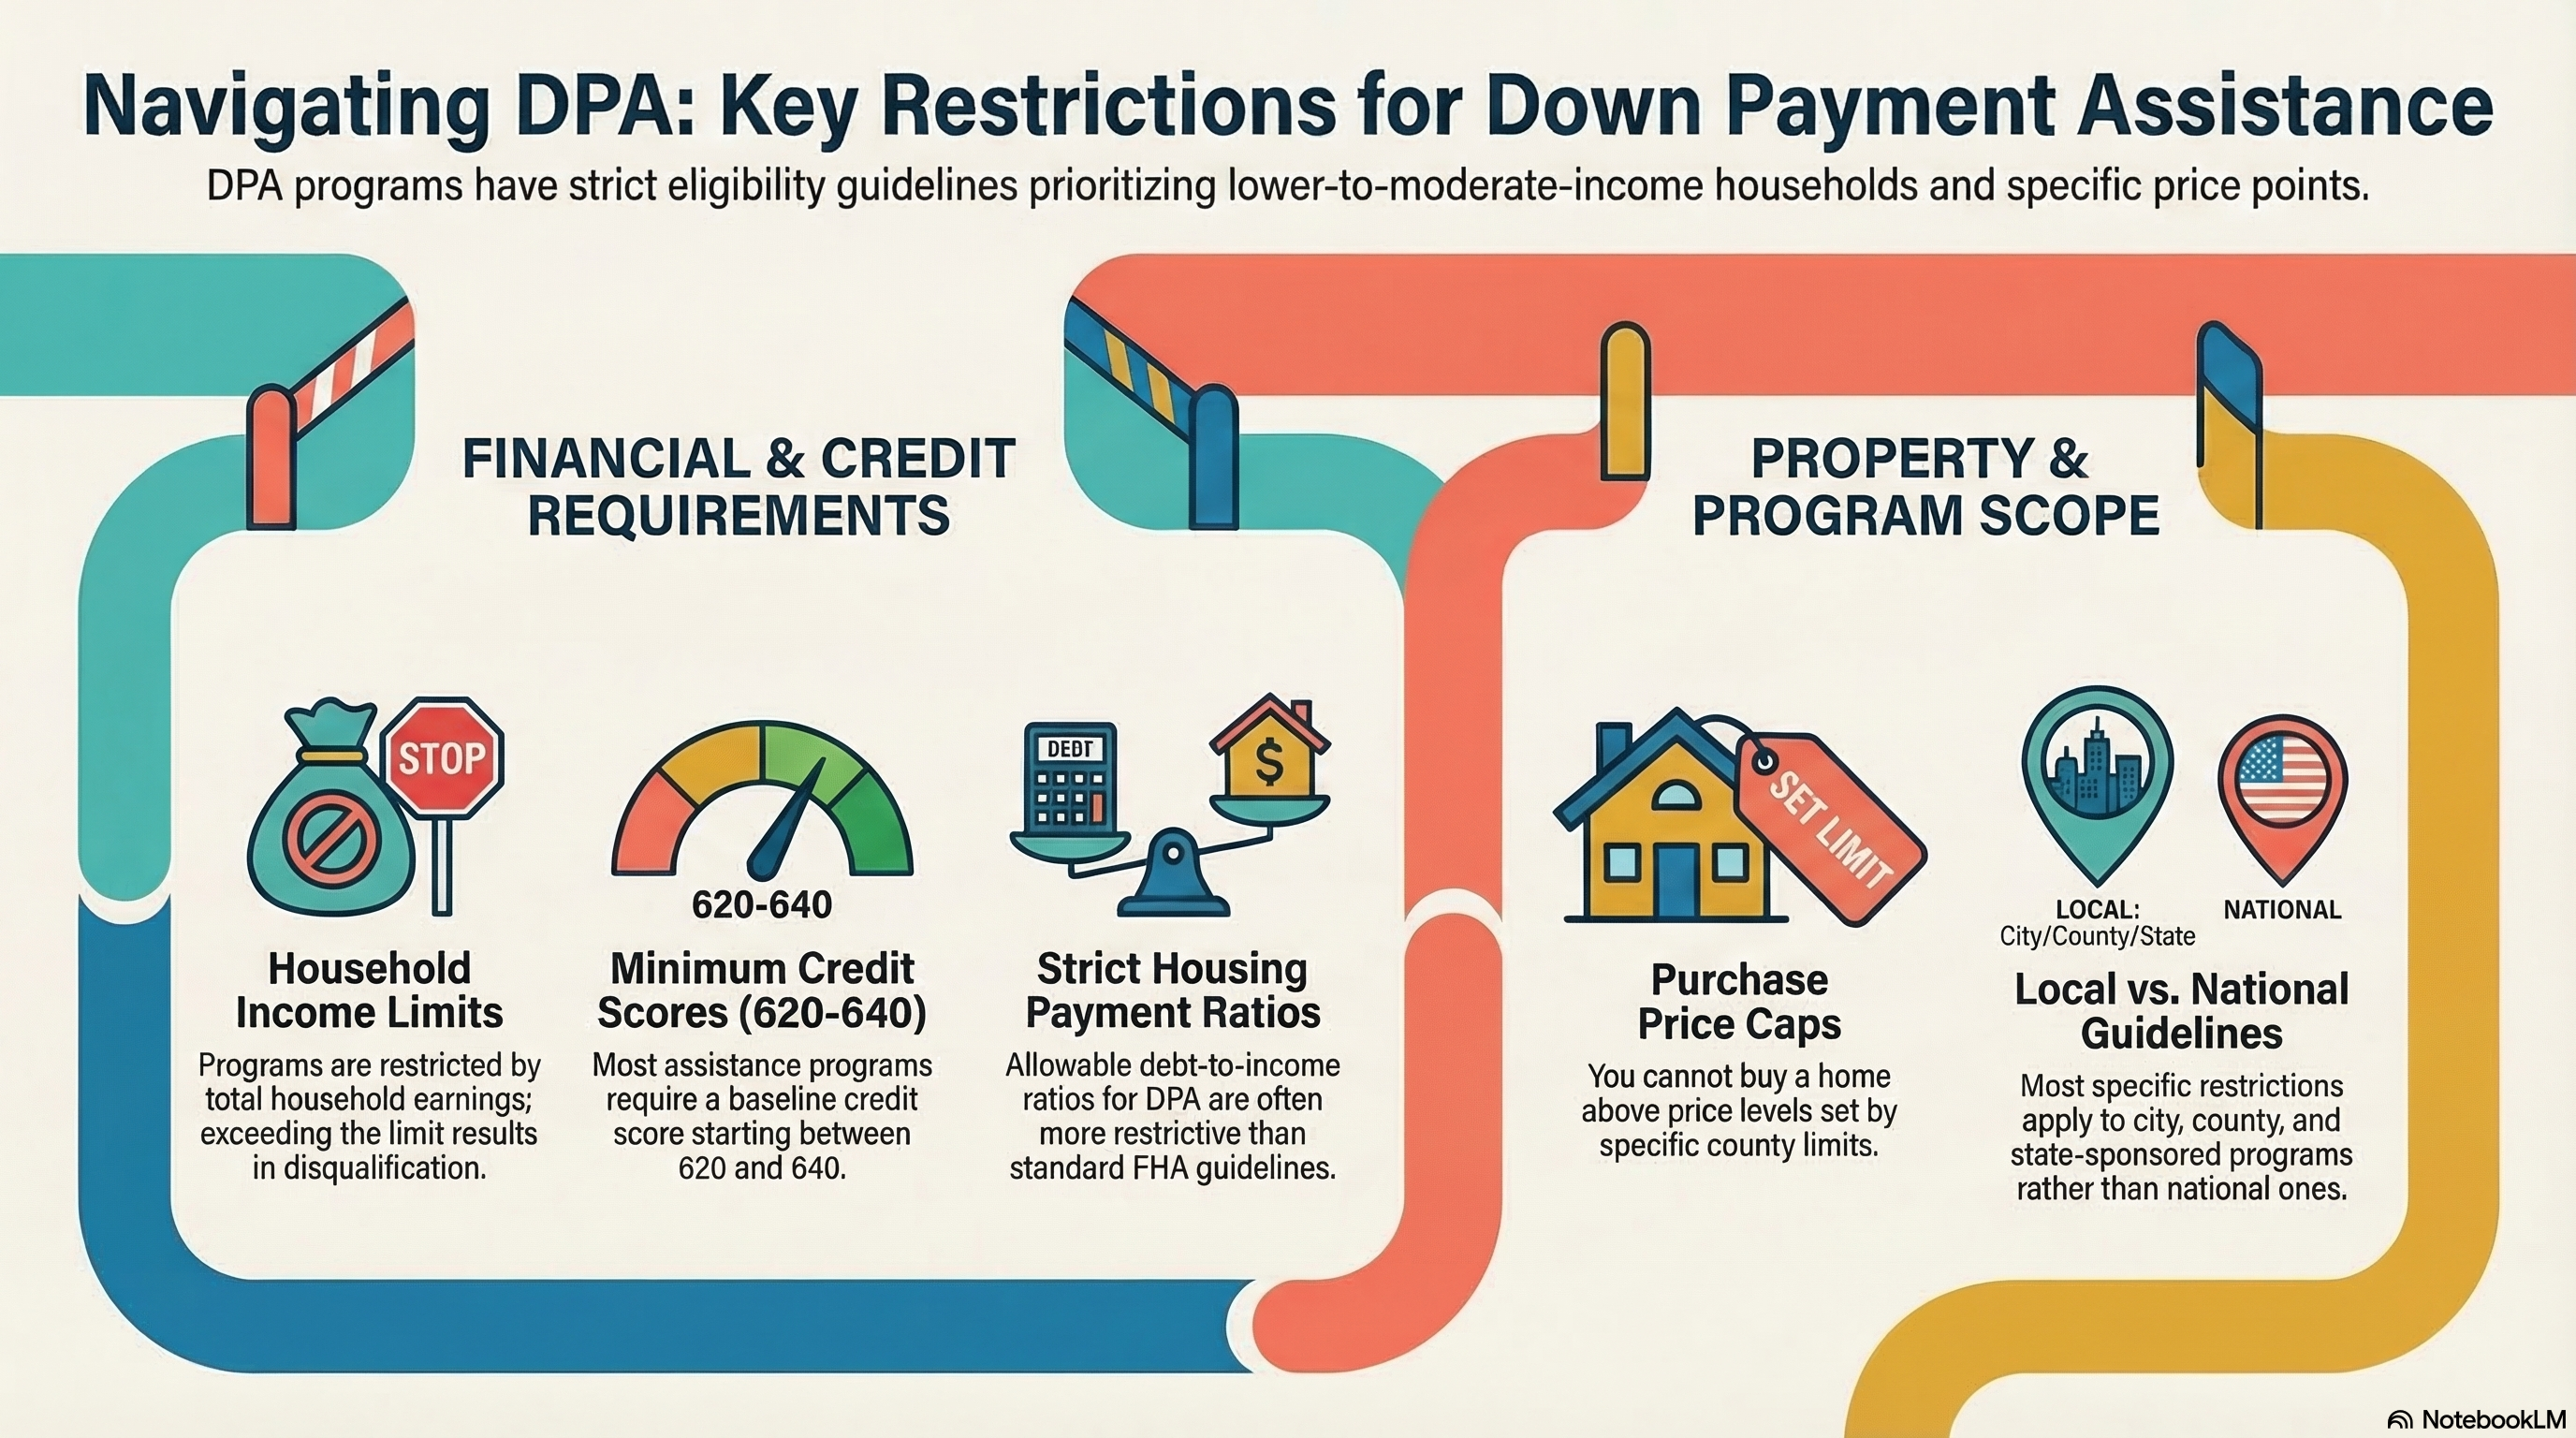
Then comes DPA's own gate, and it is usually harder: credit around 640 on many programs, an income cap measured against county area median income, price caps on the house, and the DPA second-lien payment counted in the debt-to-income ratio. A buyer can clear FHA at 600 and still miss the DPA at 640, which is exactly why the assistance question belongs at the very first lender conversation.
The honest math: the second-lien payment plus FHA mortgage insurance
Here is the cost nobody mentions on the bus. FHA carries mortgage insurance on the loan, a premium built into the payment that does not disappear on its own as your equity grows, and the DPA second lien can carry a payment of its own, commonly around $80 a month on a typical small lien.
Dollar math: the second lien at about $80 a month is nearly $1,000 a year, and it sits in the total payment next to the first mortgage and the insurance. The full monthly check on an FHA plus DPA deal is the number to qualify, and the number to budget, and the honest comparison is that total against the same house without assistance, same price, same day, on the same terms.
When the assisted total fits, the deal wins on cash. When the payment budget cannot absorb it, run the unassisted FHA number before falling for the down payment help.
When the combo wins
FHA plus DPA wins when the buyer has the steady income and clean enough credit, and lacks the cash. That is most of the first-time buyer market: steady paychecks are not the problem, the savings account was the problem, and the pairing exists to solve the savings account.
The combination is one of the strongest doors into Texas homeownership for that exact profile. And the larger point is the one Patrick keeps making with buyers: run both versions on paper, the assisted FHA loan and the plain FHA loan, and pick the one whose full monthly payment you can live with while the cash stays in your pocket.
Watch: the FHA 100% loan play, run on camera
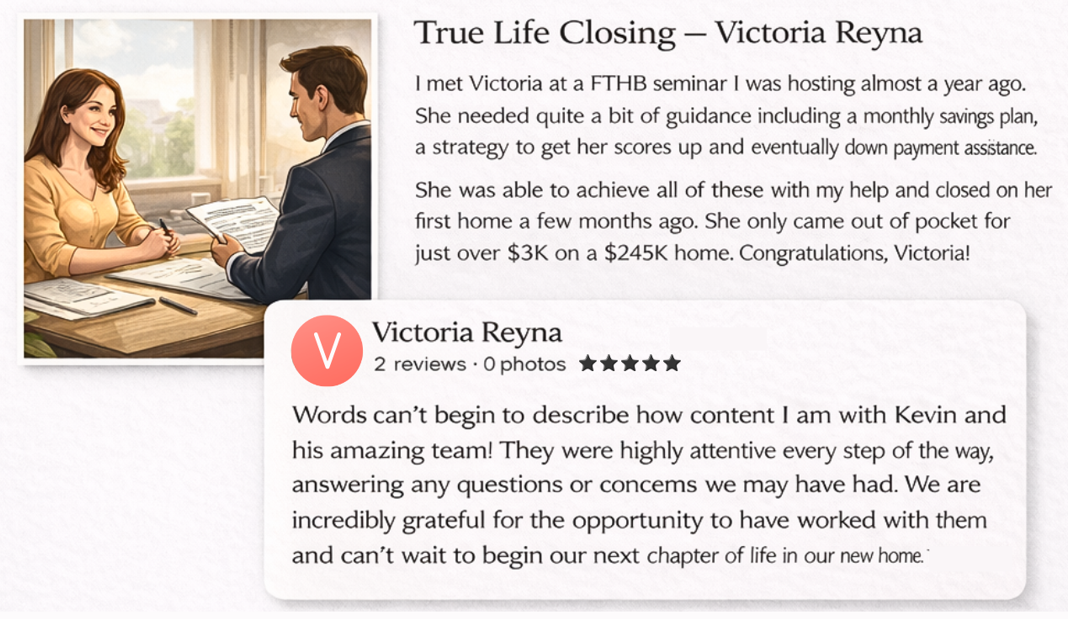
This is the video where Patrick runs the exact combination, FHA plus down payment assistance plus seller concessions, that takes a purchase down to a roughly $1,000 closing check.
Read the full transcript of this video, word for word. Or watch it on Patrick's YouTube channel.
Ask Patrick about DPA with an FHA loan
Find out how to combine down payment assistance with an FHA loan in Texas.
