
Every week a Texas buyer asks which down payment program saves them the most money, and the honest answer is the answer nobody wants to hear: it depends on your county. Pick the wrong one and you are either unqualified, over the price cap, or stuck with a second lien you did not budget for. Here is how Texas DPA actually works, who clears the gate, how to pick the right program for your county, and what the deal looks like in real dollars.
Quick Answer
There is no single best program. Texas assistance is stacked from statewide programs like TSAHC and TDHCA plus city and county programs, most of it structured as a grant or a second lien. The best one for you is the program whose income limit, price cap, and repayment terms fit your county, your loan type, and your cash.
Get help lowering your cash to close with the best DPA for you.
How Texas DPA works: state and local programs, second liens and grants
Texas runs down payment assistance on two decks. On the state deck you have the two big statewide players: TSAHC, with Home Sweet Texas and Homes for Texas Heroes, and TDHCA, with My First Texas Home and My Choice Texas Home. On the local deck sit city and county programs, and San Antonio and Bexar County have their own options that can stack on top of the state money.
The form matters as much as the amount. A true grant never has to be repaid. Most Texas assistance, though, is a second lien: forgiven after you live in the home for the required years, deferred until you sell or refinance, or repayable with a small monthly payment of its own. Same money at closing, very different long-term cost.
Dollar impact: programs typically offer assistance in a range around 3% to 5% of the loan amount. On a $245,000 purchase, 5% is about $12,250, most of it aimed straight at the down payment and closing.
The qualifying gate: income, credit, and the caps
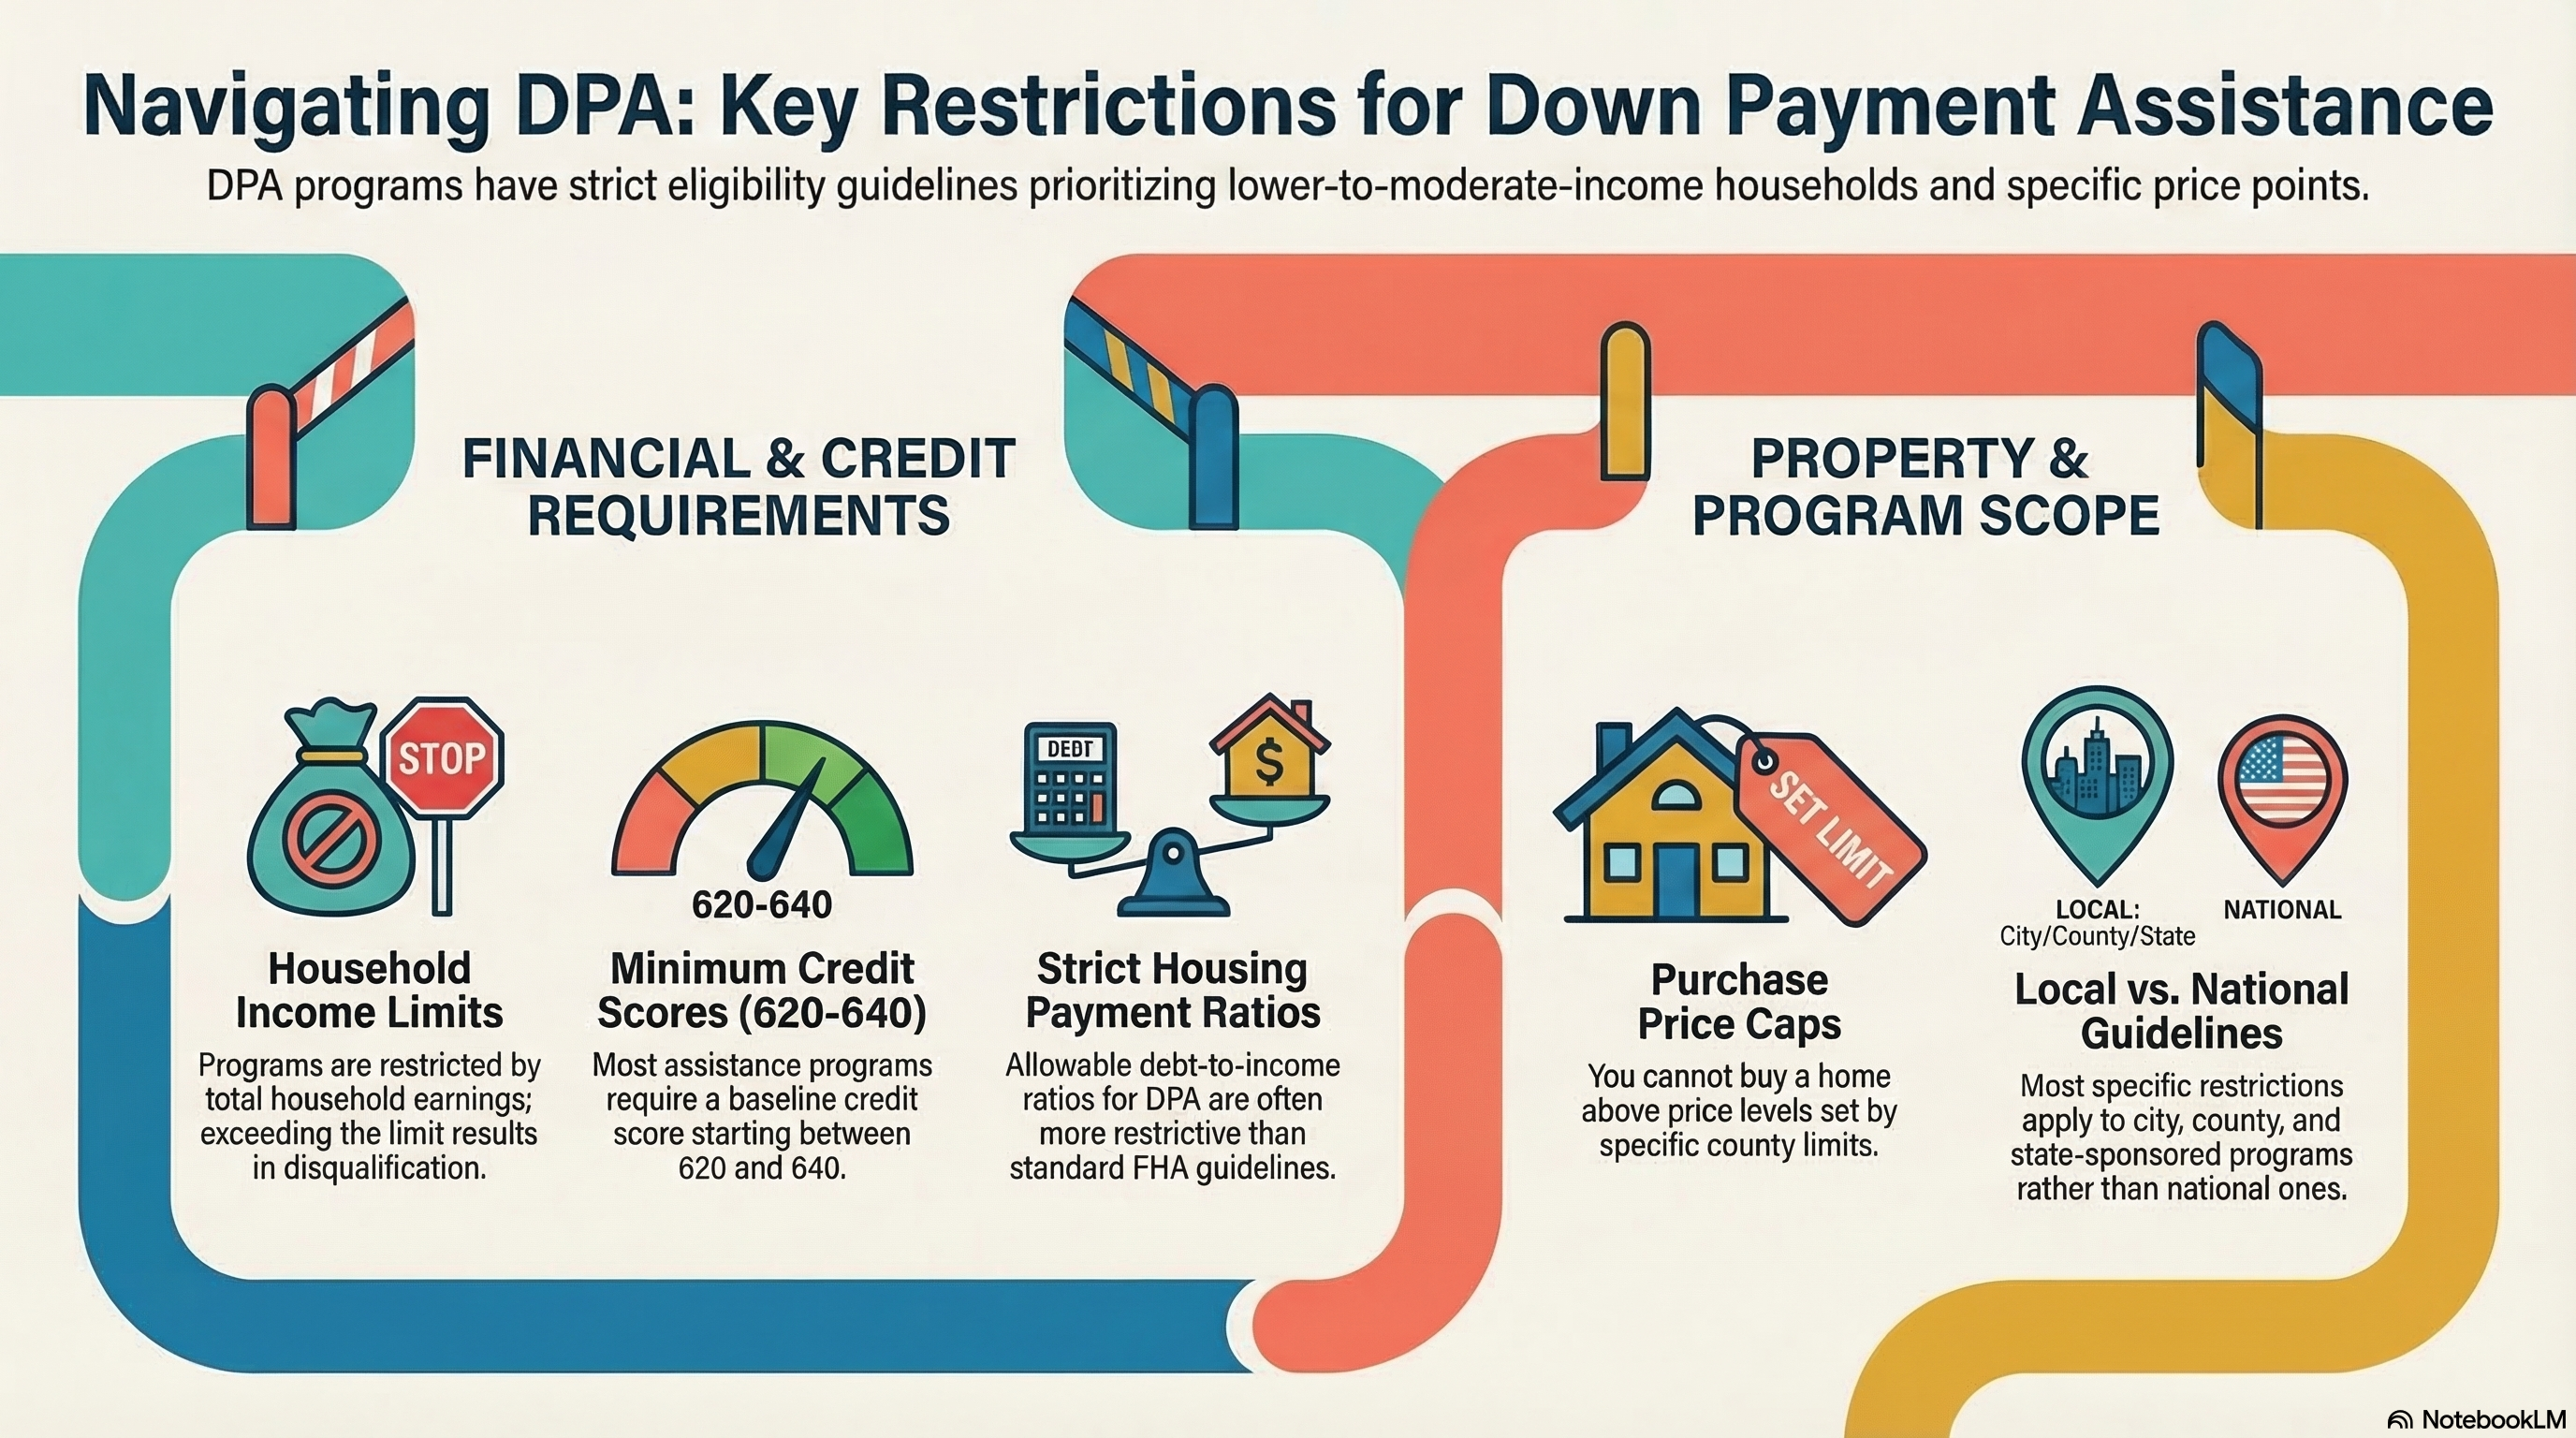
Every Texas program runs the same basic gate with different settings:
- Income under about 80% of county area median income. The limit is set per county and household size, and some programs reach higher. Go over the number and the program is gone, no matter how strong the rest of the file is.
- Credit around 640. Some programs clear at 620, but 640 is the common ask, and it sits above the underlying loan's federal minimum.
- Housing ratio often tighter than FHA. The program can draw the line tighter than the loan, so a file that passes FHA can still miss DPA.
- County purchase-price caps. The program limits what the house can cost, and the limit belongs to the county where you buy.
- Location requirement. Most programs want you living in the home, often for a minimum stretch such as 6 months, before refinancing or selling gets complicated.
How to pick the right one for your county
This is where the programs stop being interchangeable. Income limits and price caps vary by county, so the San Antonio-area program that fits a $320,000 purchase in Bexar County can be the wrong answer thirty minutes north in the Hill Country, where the caps and limits read differently.
Real-world example: a buyer can qualify for assistance in one county and miss the same program in the next county over, with the same income, same credit, and same house price. The county of the property sets the numbers, so the search should start with the county, not with the program name.
The short version of how to pick: match the program to your loan type first, because FHA, conventional, VA, and USDA all have programs that work with them, then check the county income limit and price cap against your actual numbers, then compare the repayment structure. A program you qualify for but cannot afford the second-lien payment on is not the best program for you.
The real trade-offs: compare total payment, not just money down
The marketing sells you the money down. The trade-offs are where the real decisions live. Some Texas programs charge a higher-than-market rate on the first mortgage to pay for the assistance. Some carry a second lien with a monthly payment, and even a small one, commonly around $80 a month, is real money on a 30-year loan, roughly $960 a year, every year you hold the home.
The only honest comparison is the total monthly payment: first mortgage, second lien, taxes, insurance, all of it on the same house on the same day. If Program A gives you a bigger down-payment credit but a higher rate, and Program B gives a smaller credit but a better rate and no second-lien payment, B can be cheaper every month, and the monthly number is the one that pays the bills.
A worked example: a $245,000 purchase with roughly $3,000 out of pocket
Take a first-time buyer in the San Antonio area on a home around $245,000, the shape of the deals Patrick runs with buyers every week. The 3.5% down payment is about $8,575, and closing costs push the total cash need past $12,000 on paper.
Stack the assistance: the DPA covers the down payment, seller concessions absorb a large share of the closing costs, and the buyer's own cash drops to earnest money plus the few costs the program leaves behind. The buyer closes for roughly $3,000 out of pocket.
That is the honest payoff of picking the right program for the right county: the difference between another year of rent and a $3,000 start on a home you own.
Watch: Texas down payment assistance, explained
This is the video where Patrick walks through the best down payment assistance programs available in Texas, how the restrictions work, and the two hidden costs that trip buyers up.
Read the full transcript of this video, word for word. Or watch it on Patrick's YouTube channel.
Ask Patrick about down payment assistance
Get a straight answer on Texas down payment assistance programs and which ones fit your income.
