

Quick Answer
You are closer to ready when your income is stable, debts are manageable, credit is acceptable, you can cover cash to close, and the full monthly payment fits comfortably with room for repairs and other ownership costs.
Get help planning your purchase and your financial readiness.
The six-month countdown
Ready does not happen by accident, it happens on a calendar. Give yourself six months before you want to be in a home, and the window looks like this: month one through three, save and clean up credit; month four, get pre-approved and run the real numbers; months five and six, shop, offer, and close. Buyers who compress that into weeks are the ones who panic at the closing table.
Financial readiness is more than having enough money for a down payment. CFPB's readiness checklist asks whether you have regular and reliable income, manageable long-term debts, money for a down payment, the ability to make the mortgage payment, and funds for closing, moving, repairs, improvements, insurance, taxes, and other ownership costs. [1] Consumer Financial Protection Bureau CFPB does not create one universal income, reserve, or credit-score threshold that makes every buyer ready, and neither do I.
The five-part self-check
Run yourself through these five before you look at a single listing:
- Credit. Know your middle FICO score from all three bureaus, and pull your reports for errors. Most conventional programs want 620 or better at low-down-payment tiers, FHA can work from 580 with 3.5% down, and the score you bring sets the rate you get.
- Stable income. Two years of consistent employment reads as ready. Self-employment, commission, overtime, bonuses, or a recent job change may require additional documentation, so have the two years of returns ready. [2] Consumer Financial Protection Bureau
- Savings. Cash to close covers the down payment, lender and settlement charges, prepaid insurance, escrow deposits, and other adjustments, reduced by deposits and credits. On a $300,000 house with 3.5% down, that starts with $10,500 of down payment plus the closing costs on top.
- Seasoned funds. The money in your account has to be provably yours. Lenders want to see it sit, and a big deposit that showed up last week gets a question, so move the gift money and the 401(k) loan proceeds early and let the funds season.
- Debt. Your monthly debts define your ceiling. CFPB advises avoiding new loans, large credit-card purchases, and new credit applications during the preparation period, because every new obligation shrinks the house you can afford. [3] Consumer Financial Protection Bureau
The qualification math, worked on a real income
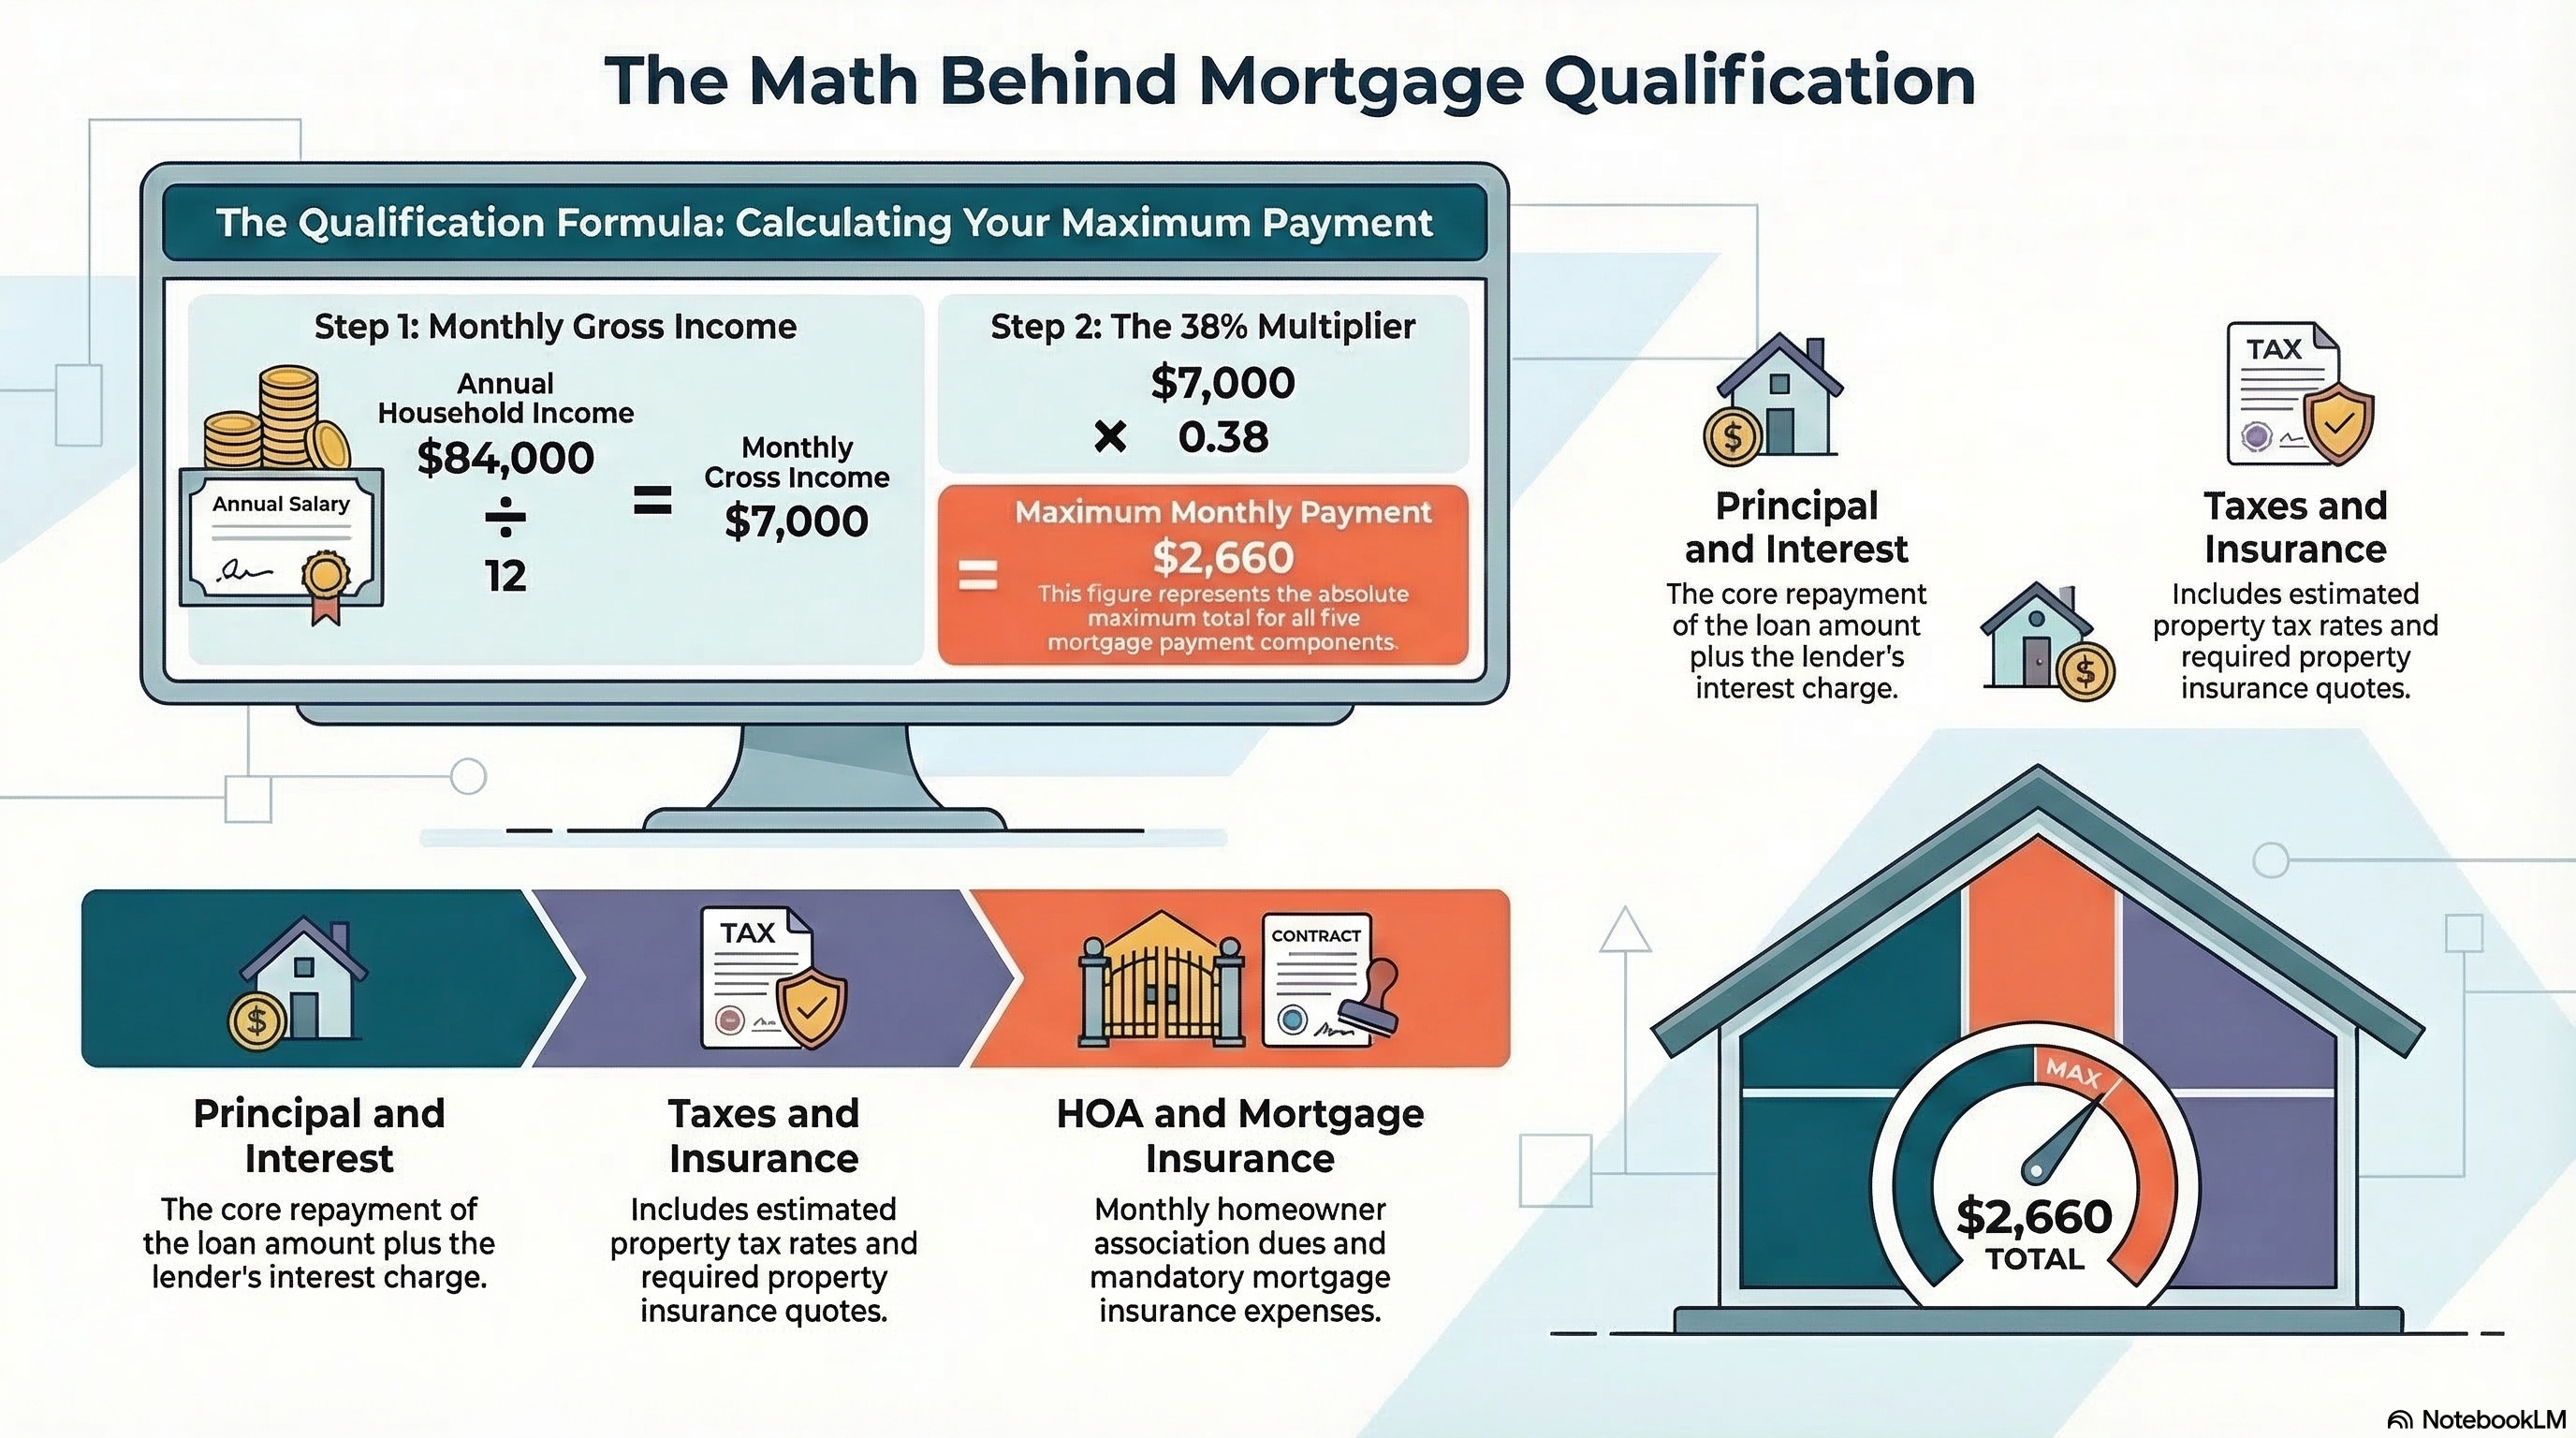
Now the part that settles the stomach. Take a household grossing $100,000 a year, $8,333 a month, with about $1,300 in monthly debts and a 700-plus credit score. At a 43% total debt ceiling, that buyer's housing payment can run around $2,283 a month including taxes and insurance, which is the payment on roughly a $395,000 home at today's buying power.
Drop the income to $80,000, $6,667 a month, and the same debt load lands closer to a $300K to $315K home with an FHA loan at 3.5% down. The numbers pivot on three dials: income, debt, and the rate you bring, and Texas property taxes and insurance sit inside the payment the whole way, because local taxing units set and collect property taxes and the bill depends on the address and exemptions. [4] comptroller.texas.gov
What that math buys
The math does not just produce a number, it produces a shopping lane. At $395,000 of buying power you are touring in one price band; at $300,000 you are in another, and they are different neighborhoods, different tax bills, and different monthly payments.
Two rules keep the math honest. First, DPA can reduce upfront cash, but it does not automatically make a monthly payment affordable, so budget the payment, not the closing check. Second, keep six months of payments in reserve after closing, because the house that still leaves your budget comfortable is the one you bought, not the one the approval letter says you can handle. Before shopping, ask a lender to prepare a conservative budget using the exact property taxes, insurance, HOA, and loan structure.
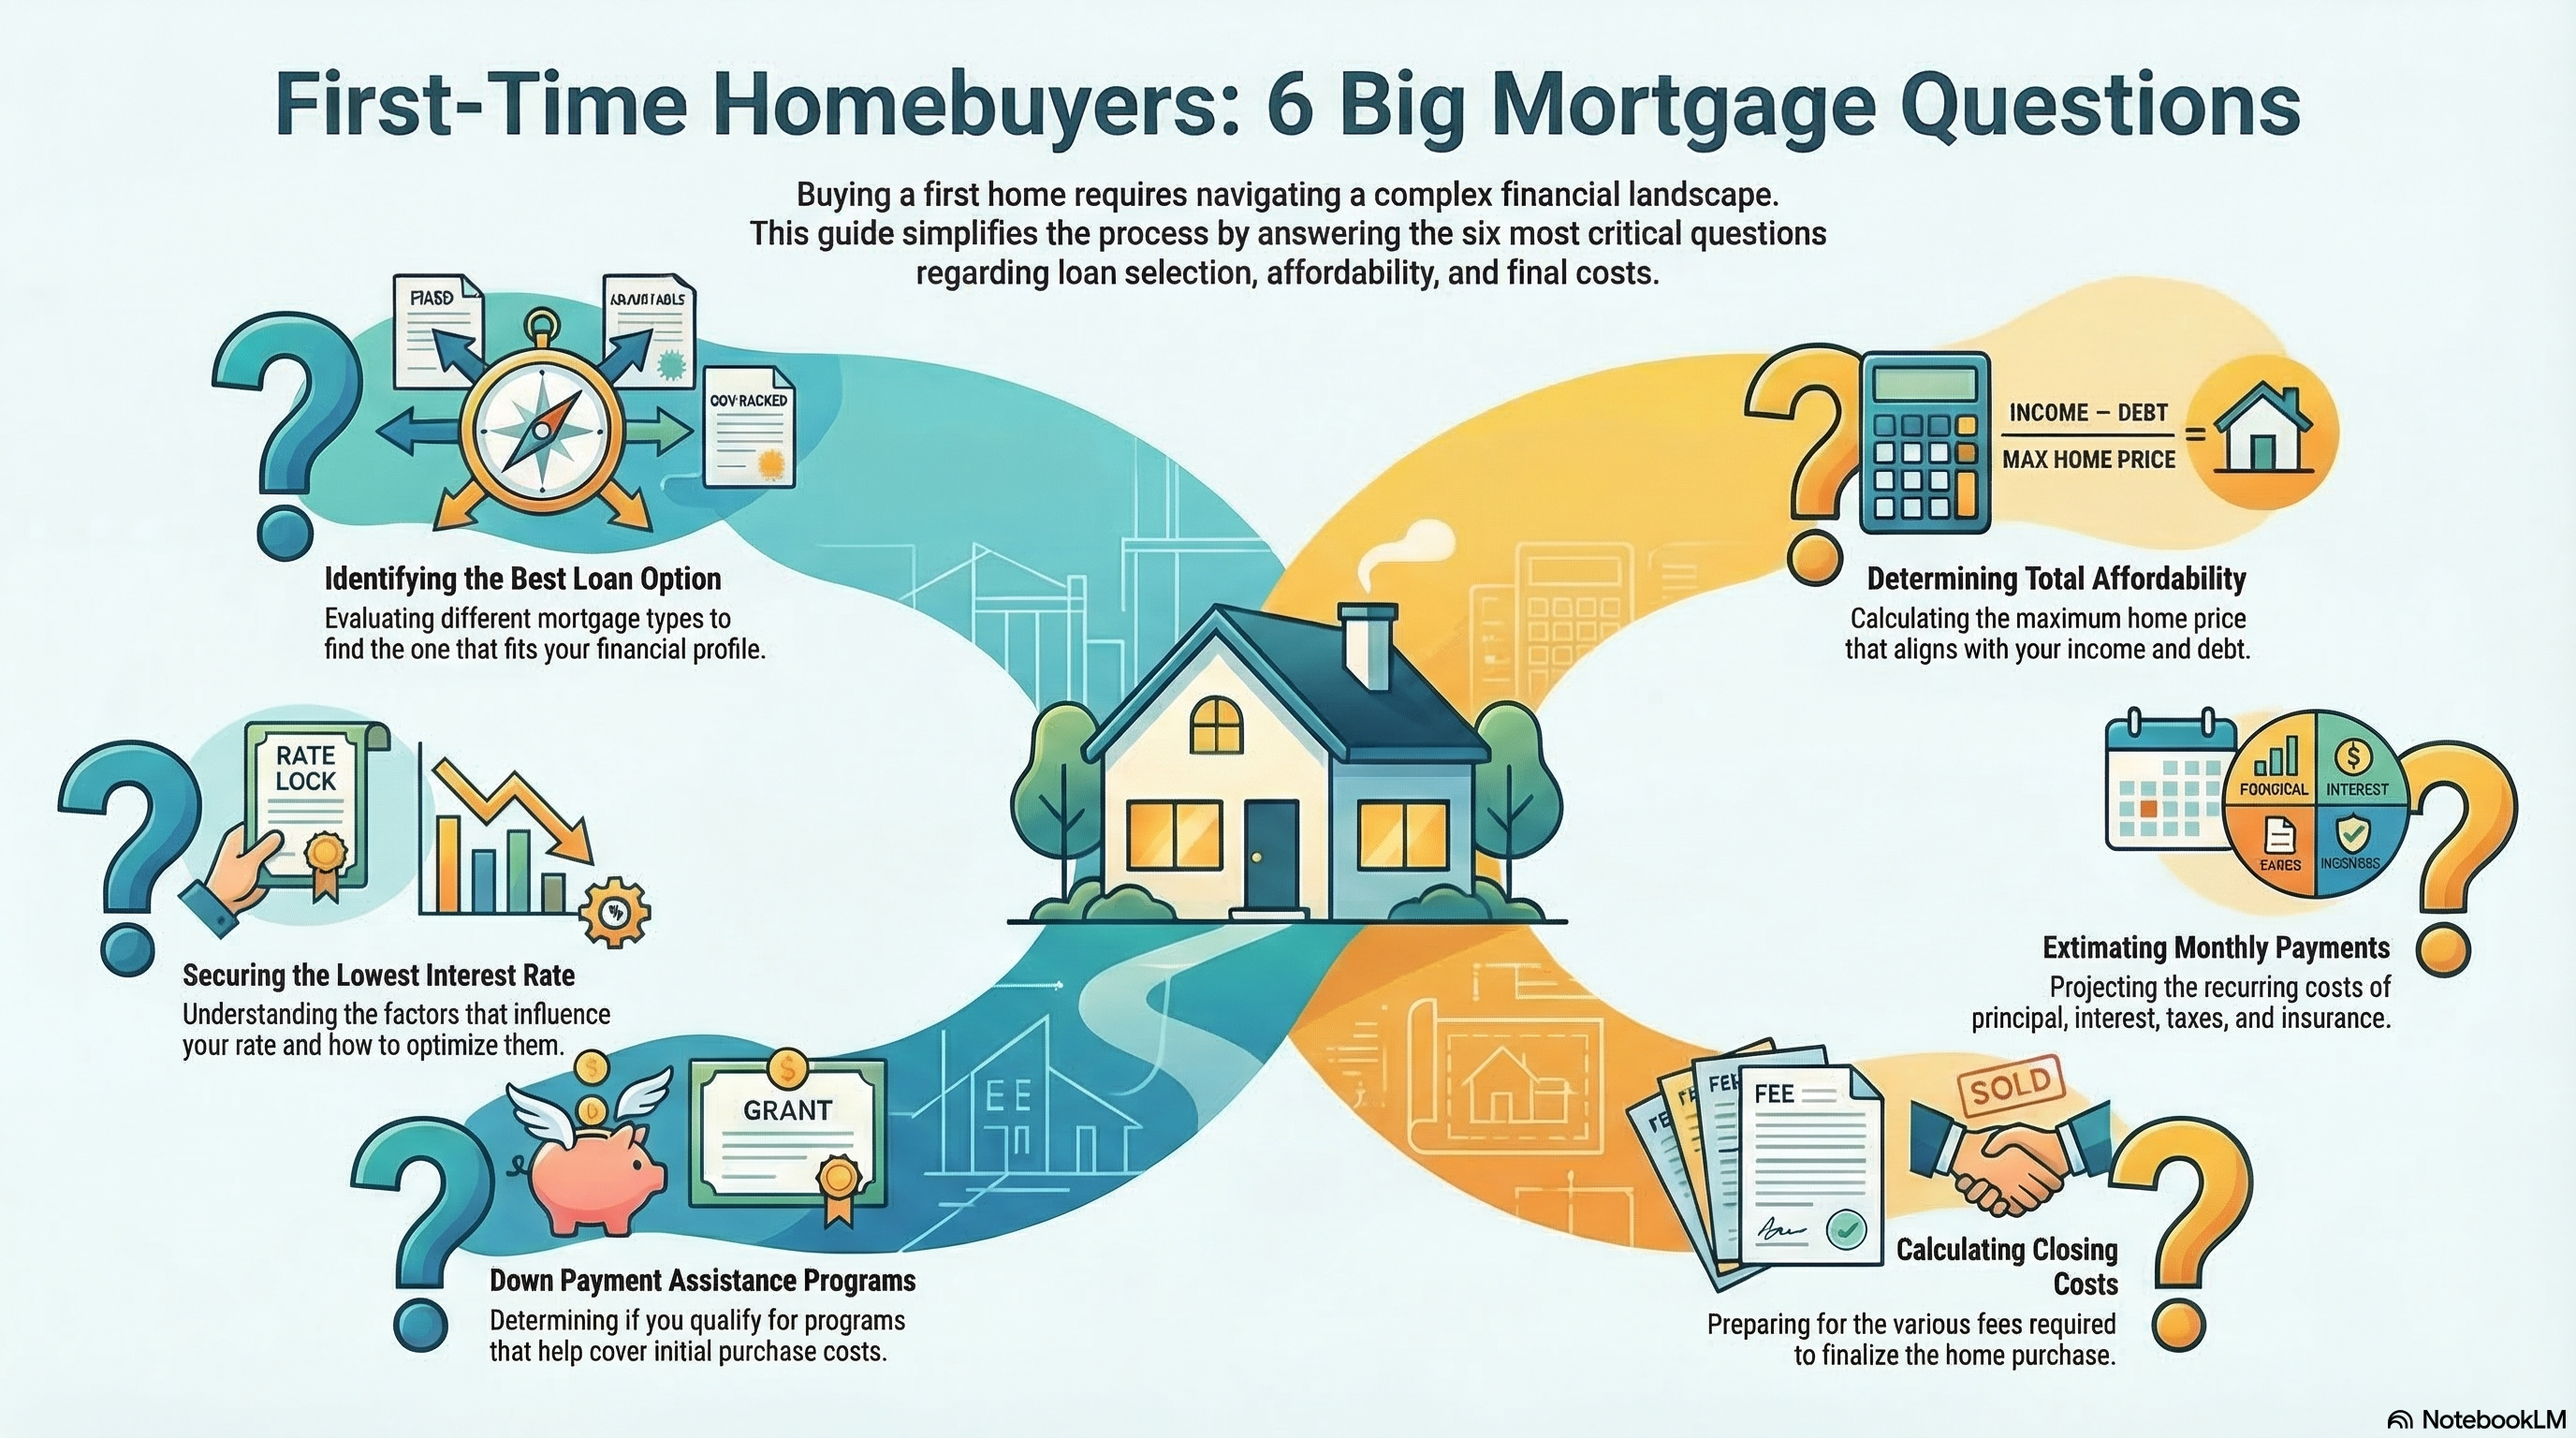
The six big mortgage questions every first-timer must answer
Before you tour, write down plain answers to these six, because they are the questions that actually decide your purchase:
- Where do I even start? The answer is a pre-approval, not a realtor or a listing app.
- How much house can I afford? The worked math above is your starting point, then the pre-approval makes it real.
- Can I buy with little money down? FHA 3.5%, conventional 3% for eligible buyers, VA and USDA zero down, and Texas DPA on top.
- What credit score do I need? 620 opens conventional doors; 580 can still buy FHA; and the higher your score, the lower your rate.
- How much are closing costs? In Texas, plan real money above the down payment, and get the exact estimate in writing before you commit.
- What should I avoid doing before closing? New loans, new cards, big purchases, job changes, and unexplained deposits. The loan is won or lost in the thirty days before closing.
Readiness vs perfection
Here is the honest truth: nobody buys their first home with perfect credit, a fully funded emergency fund, and zero doubts. If you wait for perfection, you rent for another five years and pay someone else's mortgage on your behalf.
Readiness is a checklist with a passing grade, not a perfect score: stable income, debts under control, a real credit score, cash to close, and a payment you can live with at year three. If you hit those five, you are ready, and the small imperfections are exactly what a good loan officer builds around. Run the countdown, answer the six questions, and let the math tell you when it is time.
Watch Patrick walk through how much house you can afford
This is the video where I put real incomes and real Texas payments on the board, so you can see your own readiness number before you ever tour.
Read the full transcript of this video, word for word. Or watch it on Patrick's YouTube channel.
Ask Patrick about getting financially ready to buy
Get a straight answer on savings, credit, and debt so you know when you are ready to buy.
